Blog

The financing opportunity inside Kenya’s fish supply gap

Kenya’s fish market has a sizable supply gap. In 2024, the country produced 168,424 metric tons (MT) of fish, enough to meet about one-third of its estimated annual requirement of 510,000 MT. 

The remaining gap, roughly 342,000 MT, represents about two-thirds of the estimated demand. For lenders, that scale raises a crucial question: how much can viable domestic fisheries businesses supply, and what finance would help them grow? 

For financial institutions, that distinction matters. The opportunity extends beyond financing businesses that serve Kenya’s current production base. It also includes viable hatcheries, producers, input suppliers, traders, processors, and cold-chain businesses that can help close part of the supply gap. 

The two-thirds gap does not automatically define a bankable market. Affordability, consumer preferences, infrastructure, production constraints, and market access determine how much potential demand becomes actual sales. Still, the gap’s scale suggests that the financing opportunity could extend well beyond the businesses currently visible to formal lenders. 

As the first blog in this series argued, the gap in Africa’s USD 22 billion fisheries sector presents a development challenge and a potential commercial opportunity for financial institutions that understand how different parts of the value chain operate. 

A large gap between potential demand and domestic supply 

Kenya’s fish production is struggling to meet demand. Lake Victoria landings fell 29.9% between 2021 and 2024 amid overfishing and habitat degradation. 

Kenya currently fills part of its fish supply gap through imports, using foreign exchange on a protein source that it has the land, water, and workforce to produce domestically. 

How can domestic producers capture more of this demand? The answer depends on how much local supply can grow and what capital will enable that growth. 

Expanding domestic production could reduce import dependence and create opportunities throughout the fisheries value chain. 

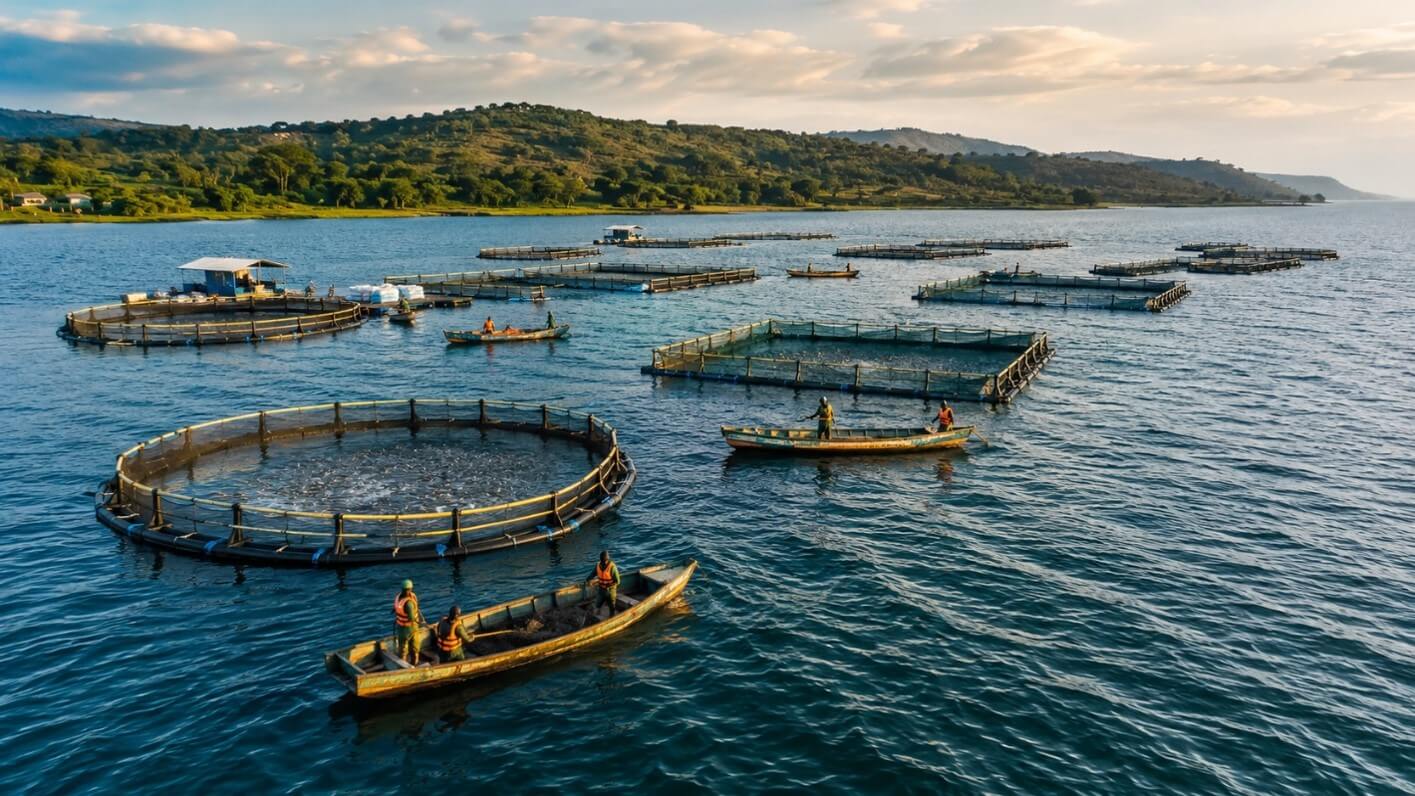
Cage farming in Lake Victoria shows how quickly managed production can reach meaningful scale. In 2024, Kenya had 5,975 operational cages managed by 634 farmers. These cages produced approximately 25,547 MT of fish and accounted for 76.4% of the country’s total aquaculture production of 33,423 MT. 

Scaling fisheries production involves far more than adding cages. Farmers need fingerlings and feed. Hatcheries need equipment and working capital. Traders need liquidity to purchase fish, while processors and distributors need cold-chain infrastructure. Each business has a distinct investment cycle, cash flow, and risk profile. 

Expansion, therefore, creates a series of distinct financing needs across the value chain. 

One value chain, very different capital needs 

MSC’s market study under the Women and Youth Economic Empowerment in Fisheries through Inclusive Market Access (WYEEFIMA) program, implemented by TradeMark Africa and the African Continental Free Trade Area (AfCFTA) Secretariat in partnership with the Mastercard Foundation program, illustrates this diversity. 

MSC’s research identifies nine fisheries value-chain actor profiles whose capital needs range from KES 1,833 (about USD 14) for a micro-retailer to KES 15.2 million (about USD 117,000) for a commercial hatchery. 

These differences matter for lenders. A lender cannot finance a trader seeking short-term working capital to purchase fish in the same way it finances a hatchery investing in equipment with a multi-year useful life. Similarly, a cage farmer’s repayment schedule must reflect an eight-month production cycle rather than the repayment pattern of a conventional retail business. 

Yet, formal finance reaches only a small share of these enterprises. MSC’s WYEEFIMA research estimates formal credit access at 9% among women and 14% among youth in Kenya’s fisheries sector. The study also found that some actor groups, including fish traders and seaweed farmers, rely heavily on informal finance. 

These enterprises have identifiable capital needs, yet formal lenders have not reached many of them. 

What early lending data shows 

Does additional finance help these enterprises generate enough income to justify greater lender interest? 

Early data from participating financial institutions (PFIs) in the WYEEFIMA program offer an encouraging signal. The analysis associates each additional unit of capital provided to fisheries enterprises with about 7.3% additional monthly enterprise income. The relationship became statistically significant within six months. 

In practical terms, every USD 1 of additional capital was associated with approximately USD 0.07 in additional monthly enterprise income. That equals about USD 0.88 over 12 months if the estimated monthly association persisted. 

Employment data points in the same direction. Between August 2025 and February 2026, 115 fisheries borrowers in the program generated 63 jobs, or about 0.55 jobs per borrower. Among borrowers who received loans above KES 100,000 (USD 771), the observed ratio was 1.33 jobs per borrower. 

The sample remains relatively small, so the pattern deserves further study as more lending data becomes available. Lenders often view larger fisheries loans primarily as a greater exposure risk. The WYEEFIMA data raises another question: could some fisheries enterprises productively absorb larger loans than lenders currently offer? 

Why lenders need a portfolio of fisheries products 

No single standardized product can close the gap. 

Closing part of Kenya’s supply gap requires different forms of finance across the value chain. Traders and input suppliers may need short-term working capital. Hatcheries and producers may need longer-tenor loans. Cold-chain operators and processors may need asset finance for equipment. Larger businesses may need trade finance or guarantees to purchase inputs at scale. 

Digital credit can meet some short-term liquidity needs. It cannot finance the full range of investments required to expand production and move more fish efficiently to market. 

For financial institutions, the opportunity lies in building a portfolio of financing solutions matched to how fisheries businesses operate. 

Yet this opportunity brings risks that lenders may struggle to assess or price. Some businesses have limited formal transaction histories or conventional collateral. Seasonal cash flows may also conflict with standard monthly repayment schedules. Capital alone cannot solve these problems. 

What can help lenders enter the sector? Better transaction data, alternative collateral approaches, guarantees where appropriate, and products structured around fisheries cash flows and production cycles can help lenders assess and manage early risks. 

Why the timing matters 

Kenya’s supply deficit is already evident, and pressure on wild-catch fisheries is increasing the importance of aquaculture and other forms of managed production. Cage farming demonstrates that aquaculture can produce at a meaningful scale when producers have suitable production systems, inputs, markets, and capital. 

Financial institutions that enter the sector now can begin building transaction histories, sector knowledge, underwriting experience, relationships with viable fisheries businesses, and portfolio data that later entrants will still need to acquire. 

Yet Kenya’s supply gap alone does not justify lending. A commercial case emerges when lenders identify businesses that can use capital productively, understand their cash flows, and structure finance around the risks they carry. 

WYEEFIMA’s early evidence suggests that such opportunities exist across the value chain and at widely different ticket sizes. For a financial institution sitting across the table from a fisheries client, the practical question is: where can it deploy capital productively, which enterprises are ready, and what products fit their operations? 

The third blog in this series examines that question through seven concrete financing use cases across the fisheries value chain. It explains how MSC works on both sides of the financing equation to make formal-sector entry viable. The lesson here is clear: Kenya’s supply gap becomes a financing opportunity only when lenders match the right capital to viable businesses across the value chain. 
Rethinking risk: A GEDSI-adjusted credit assessment tool for inclusive green finance in Indonesia

Access to finance remains a challenge for women-owned micro, small, and medium enterprises (MSMEs), especially those led by women with disabilities. Several factors limit their access to credit, such as inaccessible services, gaps in financial data, implicit bias, and unsuitable financial products.  

At the Financial Inclusion Week (FIW) 2026, MSC brought together representatives from Indonesia’s Financial Services Authority (OJK), the Terala Foundation, and KINETIK to explore how financial institutions can make green finance more inclusive.

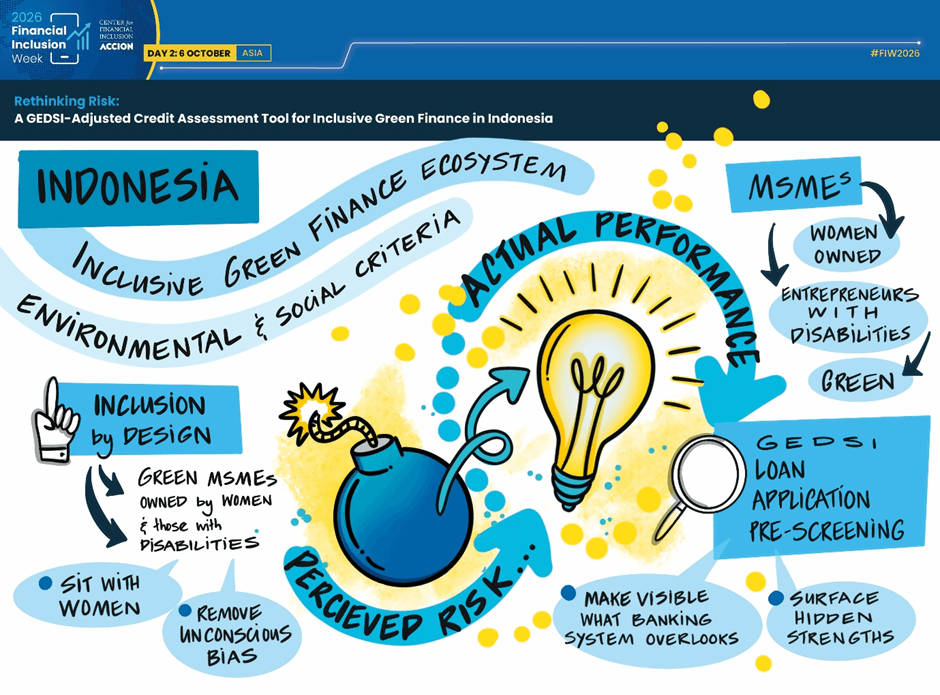
Conventional lending criteria may not capture a business’s full potential. As the illustration shows, inclusive green finance requires lenders to look beyond perceived risk and assess a business’s actual potential.

(Credit: Sonja Niederhumer’s visual illustration, developed during the session) 

Retnia Wulandari, Sustainable Finance Directorate Manager from OJK, highlighted the need to advance inclusive and green finance together. She emphasized the central role of the regulatory framework in achieving both objectives. Policies and initiatives, such as the Taxonomy for Sustainable Finance (TKBI) and gender equality, disability, and social inclusion (GEDSI)-related disclosures can support environmental and inclusion goals. 

Tien Mulyanthi, Founder and Executive Director of the Terala Foundation, highlighted the challenges women with disabilities face. She noted that exclusion can begin even before the loan application stage. Financial institutions must address accessibility barriers, data gaps, and differences in business circumstances from the outset.  

Pujiaryati Anggiasari, GEDSI Partnership Manager from KINETIK Hub, emphasized the importance of collaboration between development partners and national counterparts to turn initiatives into action. Government agencies, regulators, financial institutions, the private sector, civil society, organizations for persons with disabilities (OPDs), and development partners all have a role in addressing these interconnected barriers. 

Putu Monica Christy, GEDSI Sector Lead from MSC, introduced the Integrated Loan Application Initial Assessment Tool for GEDSI and Green Criteria. MSC developed the tool in collaboration with the Terala Foundation, with support from KINETIK. The tool offers financial service providers (FSPs) a low-barrier entry point to integrate GEDSI, disability inclusion, and green practice into loan assessments.  

As Indonesia advances its sustainable finance agenda, financial institutions can maintain rigorous lending standards and account for factors conventional approaches may overlook. 

You can access the recording of the session through the Center for Financial Inclusion YouTube Channel: https://www.youtube.com/@TheCFIchannel/playlists  

You can access the link to the Integrated Loan Application Initial Assessment Tool for GEDSI and Green Criteria: https://www.microsave.net/2026/07/13/integrated-gedsi-and-green-loan-assessment-for-inclusive-financing/  

The price and geography of financial absence

At Nyakwara beach in Kenya, Adhiambo starts her day before dawn. By mid-morning, she may have turned over stock worth thousands of shillings. By afternoon, a significant share of her earnings can go toward repaying a loan from an informal lender that charges 10% interest per day. On a simple, non-compounded basis, that is equivalent to 3,650% per annum. 

Adhiambo’s experience is not unique. MSC’s (MicroSave Consulting’s) fieldwork around Lake Victoria, conducted under the Women and Youth Economic Empowerment in Fisheries through Inclusive Market Access (WYEEFIMA) program, found many similar cases of fisheries businesses relying on expensive informal credit to finance their daily operations. 

The important question, then, is not simply why an informal lender can charge so much. It is why that lender may still be the most accessible source of working capital available to a fish trader. And why the phone in her pocket, which was supposed to make formal finance easier to access, may offer credit that is convenient, but still too costly, too small, or too short-term for the business she runs. 

Both are part of the price of financial absence. 

The geography of absence 

To understand what this absence looks like around Kenya’s Lake Victoria region, it helps to start with a place. Let us begin at Kendu Bay. 

Kendu Bay was once an important commercial center. Traders, shops, steamships connecting passengers and cargo to ports in Uganda and Tanzania, and the Kendu Show brought people and commerce to the town. Over time, Kendu’s affluence declined, Llake transport declined, road networks redirected activity, and much of the commercial center shifted elsewhere. 

Today, abandoned buildings with rusty iron-sheet roofs, collapsing stone walls, and empty streets mark the old commercial center. Fishers now use the old pier to watch the lake’s weather. Occasionally, a content creator turns up there to pose for a selfie. 


But Kendu Bay’s history matters for a different reason: financial absence cannot be easily explained by a lack of commerce.  

The same tension is visible across fisheries communities along Lake Victoria, which is a major source of fish and livelihoods. Yet, many businesses around its landing sites remain far from financial institutions. 

In 2024, fishers on Lake Victoria landed 67,575 metric tons of fish. Along Kenya’s approximately 550 km of shoreline, hundreds of landing beaches support fishers, traders, processors, transporters, and other businesses whose incomes depend on moving fish from the lake to consumers. 

A few examples suffice. Consider Sindo, a landing site and trading center in the Lake Victoria region which has no bank branch, Savings and Credit Cooperative office, or microfinance desk. Nearby island communities such as Rusinga, Mfangano, and Remba face even greater geographic constraints because access depends on boat or ferry transport. For fisheries businesses along this corridor, reaching a commercial bank branch means traveling to Mbita or Homa Bay, paying for transport costs, and losing hours that would otherwise be spent trading. 

County-level financial inclusion statistics may classify these communities as “served.” On the ground, their experience tells a different story. Even where economic activity is vibrant, access to formal finance often stops well short of the beach. 

Physical distance is only part of the problem. 

A fish trader may have no formal employment record, limited conventional collateral, or little transaction history a bank recognizes. She may also doubt whether a financial institution understands how her business works. 

This matters because the financing challenge is substantial. Ironically, discussions about closing Africa’s estimated USD 12 billion annual aquaculture financing gap often focus on product design, loan sizes, repayment schedules, collateral, and tenor. Those questions matter. Yet another comes first: where would a fish trader in Sindo or Nyakwara access such a product, even if it existed? 

MSC’s fieldwork under the WYEEFIMA program reveals the same disconnect: the fish, traders, and commercial activity are present, while suitable financial services are often absent. 

Many communities around Lake Victoria have no nearby physical financial presence. This absence also weakens trust. MSC’s research on cash-in/cash-out agents shows that access alone does not determine whether customers use financial services. Convenience, trust, and the quality of human support also shape adoption and continued use. A mobile app alone may not give a fish trader with little experience of formal finance the confidence or context she needs. 

However, digital credit has helped bridge some of this gap.  

Affordable device financing and fast approvals based on mobile money transaction histories have made digital credit one of the first formal financial services that many Kenyan households encounter. By May 2026, 252 licensed digital credit providers had issued 8.37 million loans worth KES 150.56 billion (USD 1.16 billion). 

Yet greater access has not always brought greater affordability, especially when borrowers repeatedly use short-term digital credit. For example, M-Shwari, a mobile savings and loan service offered through M-PESA, charges a 7.5% loan fee plus 1.5% excise duty for a one-month loan. In contrast, Fuliza, M-PESA’s overdraft service for completing transactions when a customer has insufficient funds, charges an access fee and tiered daily charges that vary with the amount borrowed and the repayment period.  

Cost is only one part of the mismatch. Many fisheries businesses need more capital and longer repayment periods than standard mobile credit offers. A wild-catch business with an annual turnover of KES 600,000 (USD 4,618) needs working capital aligned with its trading cycle. An omena trader may need credit through a three-week lean season. A pond farmer may need finance for an eight-month production cycle, allowing fish to reach harvest before repayments peak. 

Larger enterprises have different needs. Hatcheries and aquaculture small and medium-sized enterprises (SMEs) need structured working capital, asset finance, or trade finance, while processors may need cold-chain equipment. A small, short-term, standardized mobile loan cannot meet all these needs. 

This points to a broader challenge: access alone is not enough.  

Digital channels can reduce distance. Yet lenders must understand fisheries businesses’ seasonality, production cycles, price and input risks, trading relationships, cash flows, and limited conventional collateral before they can provide higher-value products. These include working-capital loans, asset finance, insurance, and longer-term production finance. 

The challenge combines access and fit. MSC’s research on gender-intelligent banking in Kenya reaches a similar conclusion: products must reflect how customers earn, borrow, and manage money. 

Lenders and their partners can close this product and distribution gap through trusted local intermediaries, better use of transaction data, and financial products that reflect fisheries cash flows and production cycles. The commercial opportunity is clear: these businesses already generate revenue and pay for capital, often at considerable cost, yet formal finance still underserves them. 

The second blog in this series will examine the size of that opportunity and where capital can go. For now, Adhiambo’s experience offers a clear answer to the opening question: access must combine reach, trust, and financial fit. Without all three, formal finance remains absent from the businesses it is meant to serve. 

Lowering the cost of serving clients with shared AI infrastructure

Lenders, insurers, and agricultural businesses in the same country each pay to build similar AI foundations. Building the shared parts once would help them serve smallholder farmers and small businesses better and at lower cost, while each retains control of its clients, data, and decisions. 

Take Malti, a vegetable seller in a market town in India. She needs a small loan to buy stock before the busy season. She keeps her accounts in a notebook, is paid mostly in cash, and speaks a language her lender’s systems cannot read. Field visits to serve her add costs that the interest on her loan cannot cover, so she is turned down or is offered credit on tougher terms. 

A dairy farmer in Kenya, a coffee grower in Colombia, and a sari-sari store owner in the Philippines face the same barrier. Artificial intelligence (AI) can lower it by reading a handwritten ledger from a photo, answering in local languages, and giving the lender a clearer view of risk. Doing this well takes four kinds of AI working together, and no single supplier offers all four. We propose building that foundation once, as an open commons, and seek partners to fund it. 

AI can help clients run, buy, and sell better. 

Only 56% of adults in low- and middle-income countries can raise emergency funds within 30 days, as per the Global Findex 2025, and small businesses in emerging markets face a USD 5.7 trillion credit gap (SME Finance Forum and IFC, 2019 estimate). Beyond the loan decision, AI can help these businesses run better, buy better, and sell better by finding cheaper suppliers, a government incentive they qualify for, and new buyers. The test of every tool is whether the client’s financial health, income, and resilience improve. 

A provider needs four AI capabilities at the same time. 

Four capabilities must work together to serve  Malti’s well and cost-effectively. 

  1. General reasoning, for informed decisions: The client gets coaching on running her business, and clear answers to her questions. The provider’s staff process applications and get answers in seconds. 
  2. Local language and documents, to overcome language barriers: The client gets advice in her own language, by text or by voice, even on a basic phone with a weak signal. The provider reads a handwritten form without retyping it. 
  3. Domain analysis, for practical insights: Smaller, domain-specific models analyze supply chains, market prices, or rainfall and soil. The client learns what to plant, and when and where to sell. The provider sees risk more clearly. 
  4. Traceable decisions, for transparency and accountability: The client gets a reason she can understand, and a way to challenge a decision she thinks is wrong. The provider keeps a record that its supervisor can audit. 

No single supplier offers all four. The strongest reasoning tools are rented from global companies, run outside most of these countries, and work best in English. Local language tools are improving, with regional efforts, such as Sarvam in India, SEA-LION across Southeast Asia, and Latam-GPT from Chile. Yet, as MSC’s fieldwork shows, reading handwriting in a local script or answering by voice in most African languages is not yet reliable. Domain-specific models or “small AI” models built for a particular purpose need local data. Traceable decisions require the provider to retain the evidence, rules, and model versions behind a decision, so a client or regulator can understand how it was reached.  

Few providers have the staff to run and maintain these systems internally. 

One trusted layer allows a provider to mix suppliers and keep control. 

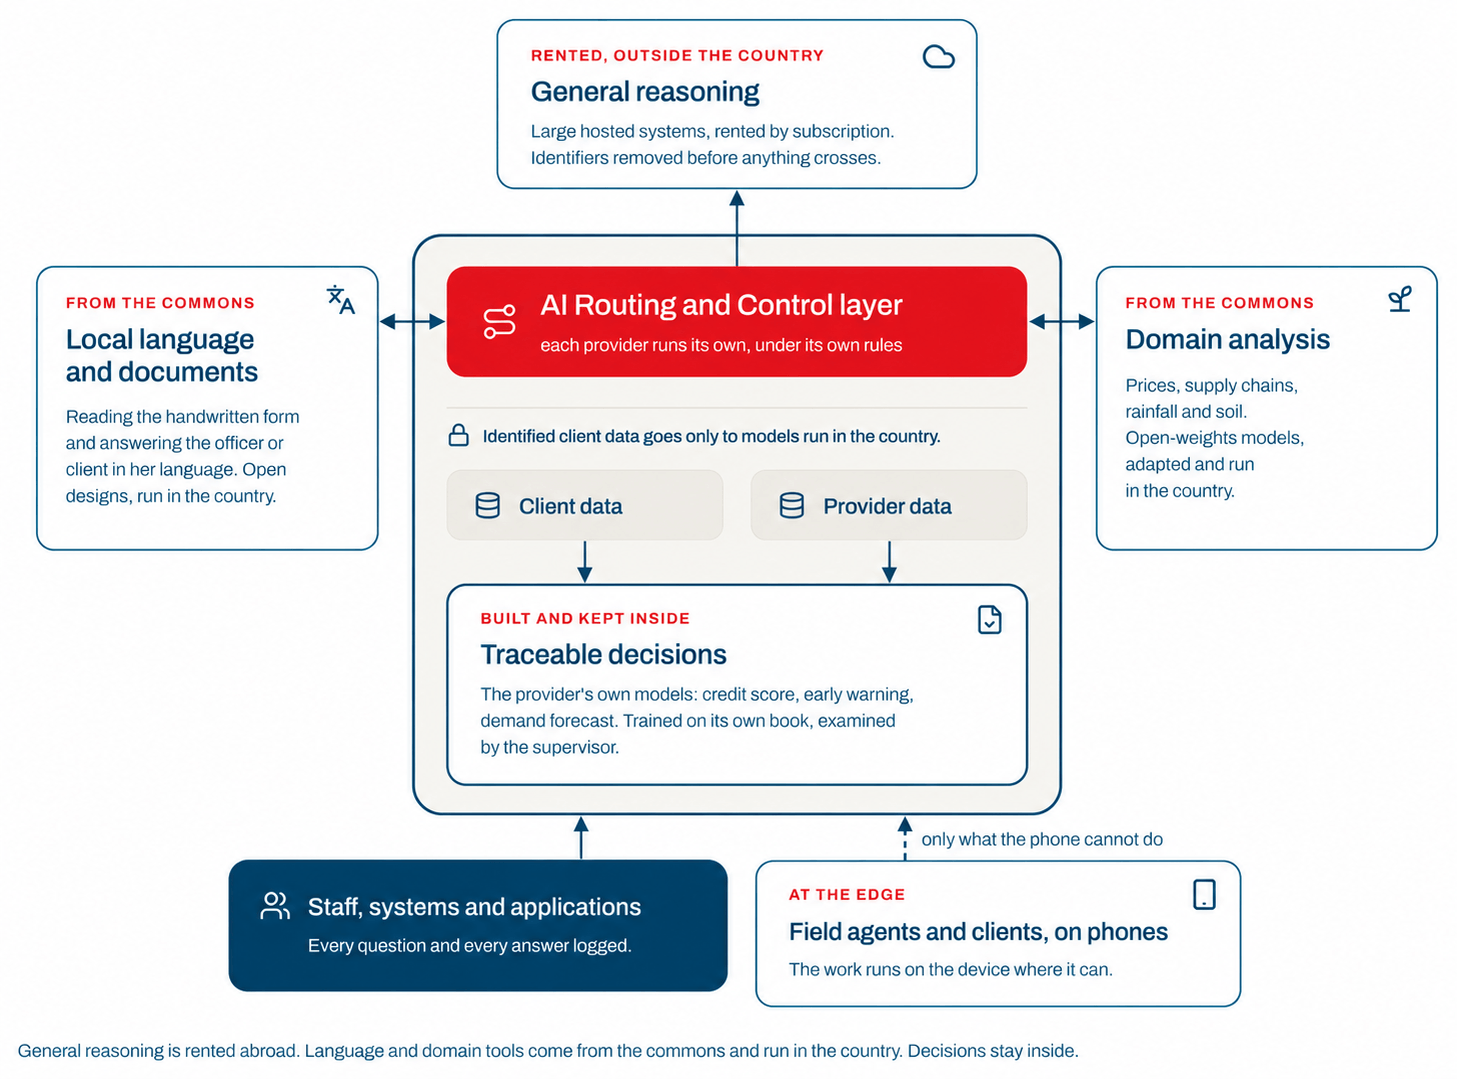
Our design places an AI Routing and Control layer between the provider and every AI system it uses, and each provider runs its own. Think of it as a switchboard with a rulebook. Every call from staff, systems, and applications passes through it, as does every request from a phone that the device cannot handle. For each request, the layer decides two things: What the AI system may see, and what it may do. 

When a model needs context, such as a client’s record, the provider’s credit policy, or a scanned form, the layer retrieves it under the provider’s permissions. Identified client data goes only to models running in the country, and identifiers are removed before anything goes abroad. When a model needs to act, such as checking a balance or pulling a bureau score, it does so through the layer, never directly. The provider writes the rules in terms its supervisor can read, and the layer logs every question, answer, and action. 

Models used for business decisions, such as credit scoring, stay inside the provider’s environment and feed its own decision engines. On the phones of agents and clients, the work runs on the device where it can, even offline, as MSC’s x-VOX platform already does. Only what the device cannot do reaches the layer. 

Diagram of an AI architecture where routing controls locally run language and domain models, keeps identifiable client and provider data in-country, records traceable decisions, and uses rented overseas systems only for anonymized general reasoning.

Because every call passes through one place, the provider can change suppliers as technology, prices, and regulations change, as long as the new system’s license allows commercial use, which some open models, such as InkubaLM, do not. While building this design is one thing, running it is where many providers will struggle. 

Build the shared parts once. 

Take 12 financial service providers in one country. They share a supervisor, an identity system, a payment network, and a set of languages, yet each builds the same connections, language tools, and tests alone. Each still funds what it competes on from its own balance sheet, and without peer evidence of a return, most boards wait. Little outside capital fills the gap. As of September 2026, financial inclusion and agriculture received USD 445 million across 12 countries, of the USD 90 billion in AI capital tracked by the Accendo Capital Flows Map in emerging markets. That is half a cent in every dollar, and nearly all of it went to single firms. 

We propose building an open commons, held by a nonprofit, which publishes three things: An open design for the layer, local-language tools, and domain-specific models with open weights that anyone can inspect. Each provider implements them locally on its own systems, under its own rules, and adapts them to its own market. Providers gain lower costs, peer results before they commit, and common standards that let them change vendors, while each remains accountable to its supervisor.  

Grants would build the commons, and member fees would maintain it. We seek funding partners who back shared infrastructure, and want to hear from providers, vendors, and supervisors who see the problem differently. 

Malti the vegetable seller will never see the AI Routing & Control layer. She will see a lender who can read her notebook, answer her in her own language, and offer terms that work for her business. A shared foundation makes that affordable for every provider in her country. 

This is the first of four parts. Part two goes deeper into the architecture: The walled, gated garden that sets what a provider owns and what it rents, how the layer works on devices, and how the commons is governed and funded. Part three looks at the risks, including shared models that fail together, and how the design answers them. Part four sets out named asks to funders, supervisors, and providers, and a first group of providers in one country. 

This blog is part one of a four-part series by Accendo Associates and MSC (MicroSave Consulting). 

More to come. 

The intelligence belongs on the device

This is the second in a two-part series on rethinking artificial intelligence (AI) delivery for agriculture, based on MSC’s experience as we built digital farmer services (DFS). 

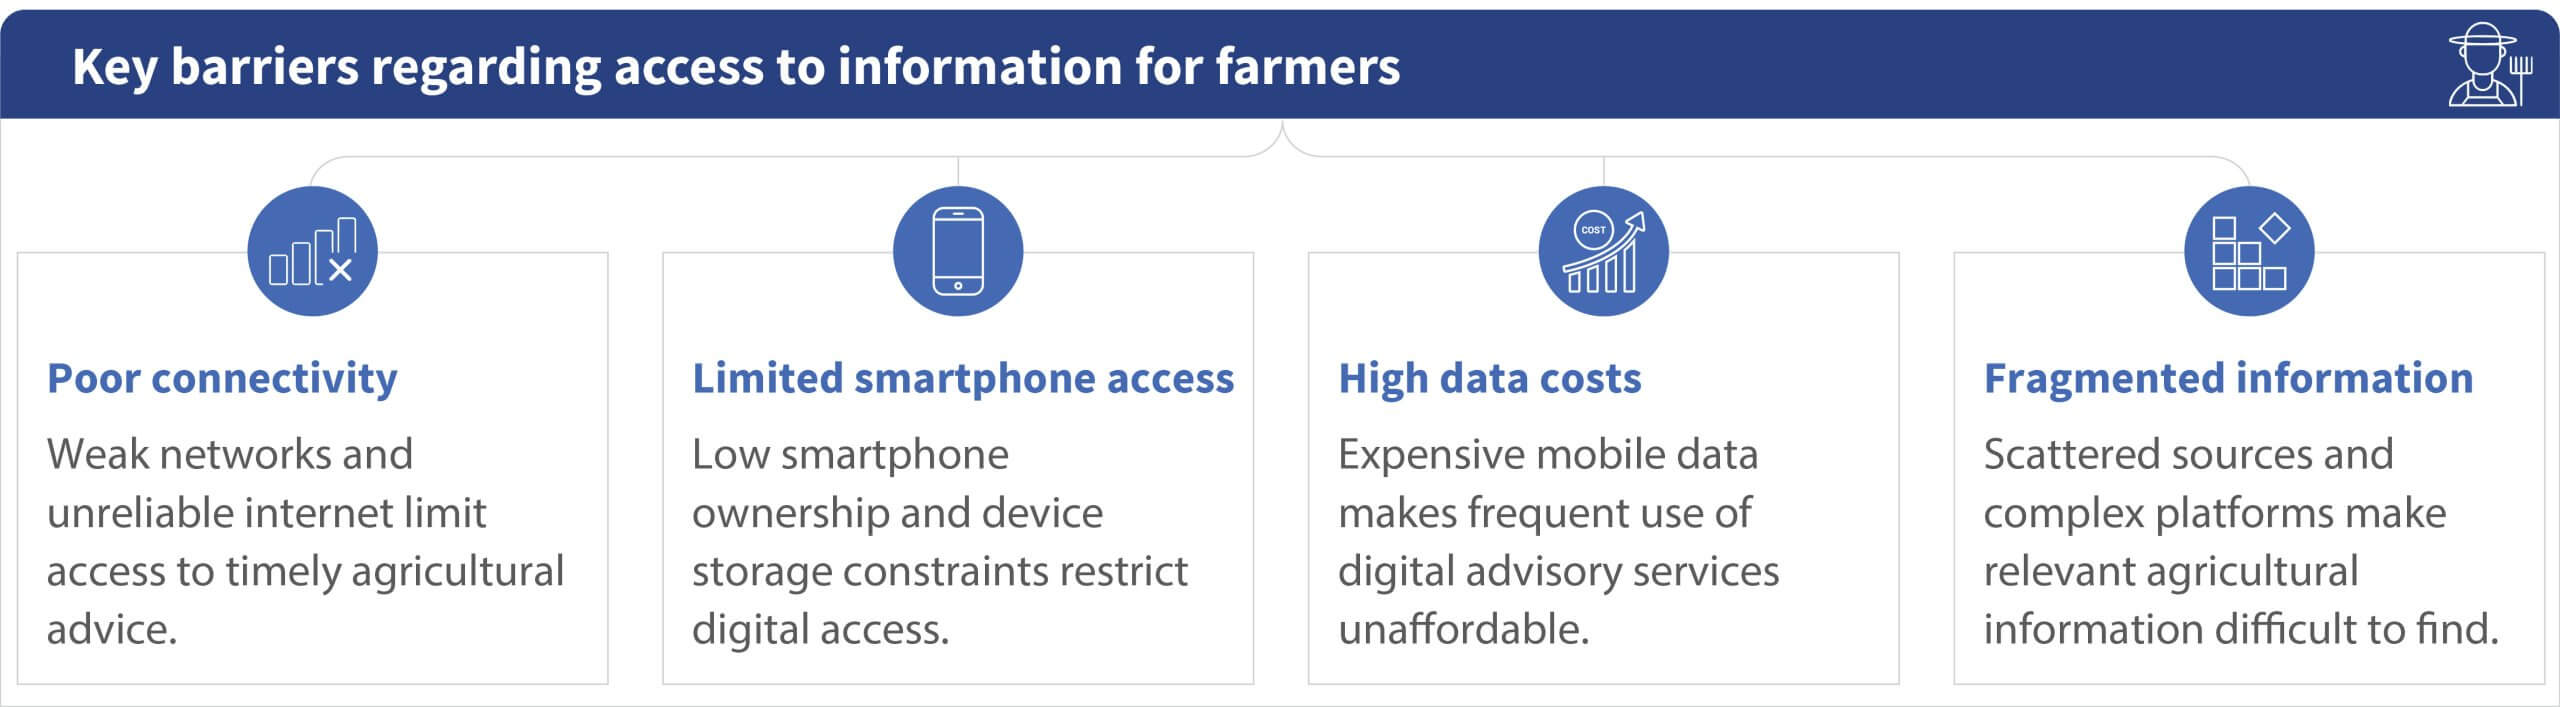
Infographic showing four barriers to farmers’ access to information: poor connectivity, limited smartphone access and storage, high mobile data costs, and fragmented information across scattered sources and complex platforms.

The first blog in this series, Why digital farmer services so often fail, argued that most AI platforms for farmers assume a decent phone, a stable connection, and cheap data. Farmers rarely have all three. Device memory runs out before the app does, a single advisory photo eats through a day’s data plan, and a dropped connection forces the network to resend the same data two or three times over.  

Platforms should depend less on the network where coverage is the main constraint. This benefits farmers who use the technology and agents who assist them. Bihar Krishi shows how this approach works. MSC helped design this government-owned digital platform targeting farmers in Bihar for the state’s Department of Agriculture. When the platform launched in 2023, farmer information and services, such as programs, market prices, and weather information, sat across separate systems. Bihar Krishi brought these services together.  

Bihar Krishi was built as a mobile app from the start. While a web version is also available, it serves a different purpose. Village-level assistants use it to help farmers who are not yet using the app themselves. 

The conversational AI feature came later to help farmers get the information they need without having to work out which menu or service to use. The AI interprets the question and directs the farmer to the relevant answer. Maharashtra’s MahaVISTAAR and the central government’s Bharat-VISTAAR platform use a similar approach. For example, “tell me more about maize” could refer to crop, seed availability, pest control, or a government program. 

Because Bihar Krishi added conversational AI to an existing platform, system questions are processed on a server, and the answer is sent back to the farmer. This approach made sense when Bihar Krishi was built. However, for AgriVOX, we asked what if more of the intelligence could sit on the device, so the platform depends less on the network?  

AgriVOX is the first version of X-VOX, MSC’s device-first product architecture for agriculture, finance, health, and other sectors. It is currently in testing. AgriVOX resolves a query in the following sequence, which stops when it finds an answer: 

  • A local intent classifier checks a compact FAQ database shipped directly inside the app. If the answer is already there, it returns instantly without a network call; 
  • If the answer is not in the app’s database, a server-hosted large language model answers anything the local database cannot, exactly as most current platforms do today; 
  • If the LLM does not have the answer because the question requires live data, it uses the Beckn protocol. The basis for Beckn is the same open, decentralized-network standard behind India’s Open Network for Digital Commerce (ONDC) and OpenAgriNet. It connects to external service providers for information no app can hold locally in advance, such as a live government program registry, current weather, or soil-testing results. 

The sequence works for farmers or people who assist them. A seed or fertilizer retailer at the counter or a village-level entrepreneur gets the same instant local answer. The system can escalate queries to a server or retrieve live program or price information. A smart intent-selection system helps route each question to the right service. 

Consider a real AgriVOX query: “I want to grow maize in the coming season. How should I prepare for it?” The platform divides the request into questions that different services can answer. The standard maize-growing procedure for the season comes from the local FAQ database. The system reads the current date to infer the season and respond without a network call. The local database can also handle field preparation, such as irrigation and ploughing. Yet, how, where, and through what mechanisms the government can help require checking live program eligibility against the farmer’s own demographic details, plus current seed and fertilizer vendor availability and nearby storage or logistics options. The server’s large language model (LLM) can reason through this, while the rest needs the Beckn-protocol lane to a live network source. 

Photo-based queries, such as a crop-disease diagnosis, follow a different path. Image-based identification needs a Vision AI model too large to run on a farmer’s phone, so this step goes to the server, which limits a single combined request. If the connection drops mid-transfer, only the failed lane is retried, with compression applied to that retry, not the entire upload resent from scratch. This is the problem Part 1 described with ordinary retry behavior. 

A second component, the FAQ-feeder, keeps the local database growing. It periodically reviews questions that had to be escalated to the server, converts the recurring ones into new FAQ entries, and, after a human review step, pushes them back down to the device. The app still needs to connect periodically to pull these updates, but it depends much less on the network. 

The first blog argued that most farmers’ phones lack memory to spare. Common app sizes put that constraint in context. WhatsApp’s Android app runs roughly 87 MB, and Facebook Messenger installs at about 97MB. Among agricultural apps, Plantix installs at roughly 21.48 MB, and DeHaat Kisan at 34MB. 

AgriVOX’s local FAQ corpus, more than 2,000 entries deep, takes up just 4MB. The full app, corpus, source-classifier, interface, and runtime libraries together total about 15 MB. This is still smaller than every app above—essential on a 2 or 3 GB device that already carries several of them. The same holds whether the device belongs to a farmer or to the retailer and village-level entrepreneur who often advises one. The device-memory constraint we mentioned in the earlier blog is real, but it applies to heavy, general-purpose apps rather than intelligence designed from the outset to fit. 

After the FAQ feeder has learned common questions in a district for one or two seasons, the local layer may answer half of farmers’ text and voice queries. Photo-based diagnosis always needs the server. However, for ordinary advisory questions, every locally answered query returns instantly, spends no data, and carries none of the retry-multiplication risk described in the previous blog. 

The financial impact scales with where the farmer lives. At roughly USD 0.16 per GB in India, the savings from a handful of daily queries are small, since Indian data is already inexpensive. At the Sub-Saharan African average of USD 3.31 per GB, the same reduction, halved, amounts to roughly a dollar or more per month on AI-related traffic alone. This saving matters more to households that carefully ration data spending. 

Local processing also makes the service more reliable. Half of conversations no longer require a nearby tower, a strong signal, or a successful first transfer. Agents who answer several questions each day can provide consistent advice even without a live connection. 

Everything so far in this blog assumes that the farmer has a phone, even an old one, on a slow network. That assumption does not hold in much of Sub-Saharan Africa, where network costs are high and mobile penetration is low and few farmers own a device. No AI architecture, edge, or server changes who owns a phone. 

However, someone in that same village usually does. Banking agents, mobile-money agents, and input and output retailers need phones to run their businesses. Agricultural extension has an obvious channel through the same agent who advises farmers directly, using a tool most farmers could never own themselves. 

A device-first architecture can therefore influence whether agents adopt the tool. A server-dependent AI advisory tool charges the agent a network cost on every query, for every farmer, all day. People who run a business on thin margins may find the recurring cost harder to justify. A device-first tool, such as AgriVOX, answers most of that same volume from the local FAQ layer, at close to no marginal network cost per query. It does not ask the agent to absorb a growing data bill in exchange for giving better advice. 

In these markets, agents offer a more realistic route than direct use by farmers. Established, trusted agents can use a low-cost tool to provide better advice. AgriVOX can make the agent’s advice better without making their business harder to run. 

Voice interfaces are also moving from servers to devices. Lightweight text-to-speech models fine-tuned on AI4Bharat’s open Hindi voice data now run entirely offline, on-device, in real time, using compact exports instead of a cloud call for every sentence spoken back to a farmer. Quantized models with roughly a billion parameters can now run on ordinary phone hardware without an external API call. Every layer of the interface a farmer touches, text or voice, is becoming something a modest device can hold on its own, extending local processing one layer higher, to the interface. 

AgriVOX does not solve the three constraints this series has described. Fixing rural bandwidth, closing the smartphone affordability gap, and rewriting the economics of mobile data are larger interventions for other actors and other debates. AgriVOX designs around those constraints as they stand today, so that adoption and inclusion do not have to wait for the larger interventions to arrive first. 

The distinction is the whole point. A technologist’s instinct is to build toward the best available benchmark, the fastest model, the newest capability, and assume the infrastructure will eventually catch up. MSC’s instinct, shaped by work closer to the ground, is to start from the stakeholder, whether a farmer or a retailer, and village-level entrepreneur advising them. We look at the phone they use, the signal they can get, and the data plan they can afford this season. The intelligence belongs on the device because a farmer can use it today. After sufficient field testing, the next post in this series will report how AgriVOX performs in practice. 

Why digital farmer services so often fail

This is the first of a two-part series on rethinking AI delivery for agriculture, based on our experience building digital farmer services (DFS). 

What happens when an AI tool designed to help a farmer cannot reach them when they need it most? The answer reveals a problem that goes far beyond the technology itself. Many artificial intelligence (AI) platforms built for farmers still begin with a simple picture: a farmer with a decent smartphone, a stable connection, and cheap data. 

For smallholder farmers, these three conditions rarely reflect reality. The gap between these conditions and farmers’ realities matters more than AI quality. It helps explain why many farmer-facing tools work in a pilot but fail once they reach real users.  

A farmer in a village three hours from the nearest town points their phone camera at a wilting maize leaf. They need an answer before the disease spreads further. The app opens, but the upload stops. Their two-year-old phone cannot handle the camera and upload simultaneously. The nearest tower is congested, so the connection times out.  

They buy a data top-up that they can barely afford. However, the problem continues. They cannot get a usable connection before the evening. The next morning, they walk to town for advice from an agri-dealer instead. They are not an exception. Their experience is common among smallholder farmers across India, Sub-Saharan Africa, and South Asia. They represent the user that server-led AI designs often overlook. 

Design for the phones farmers use  


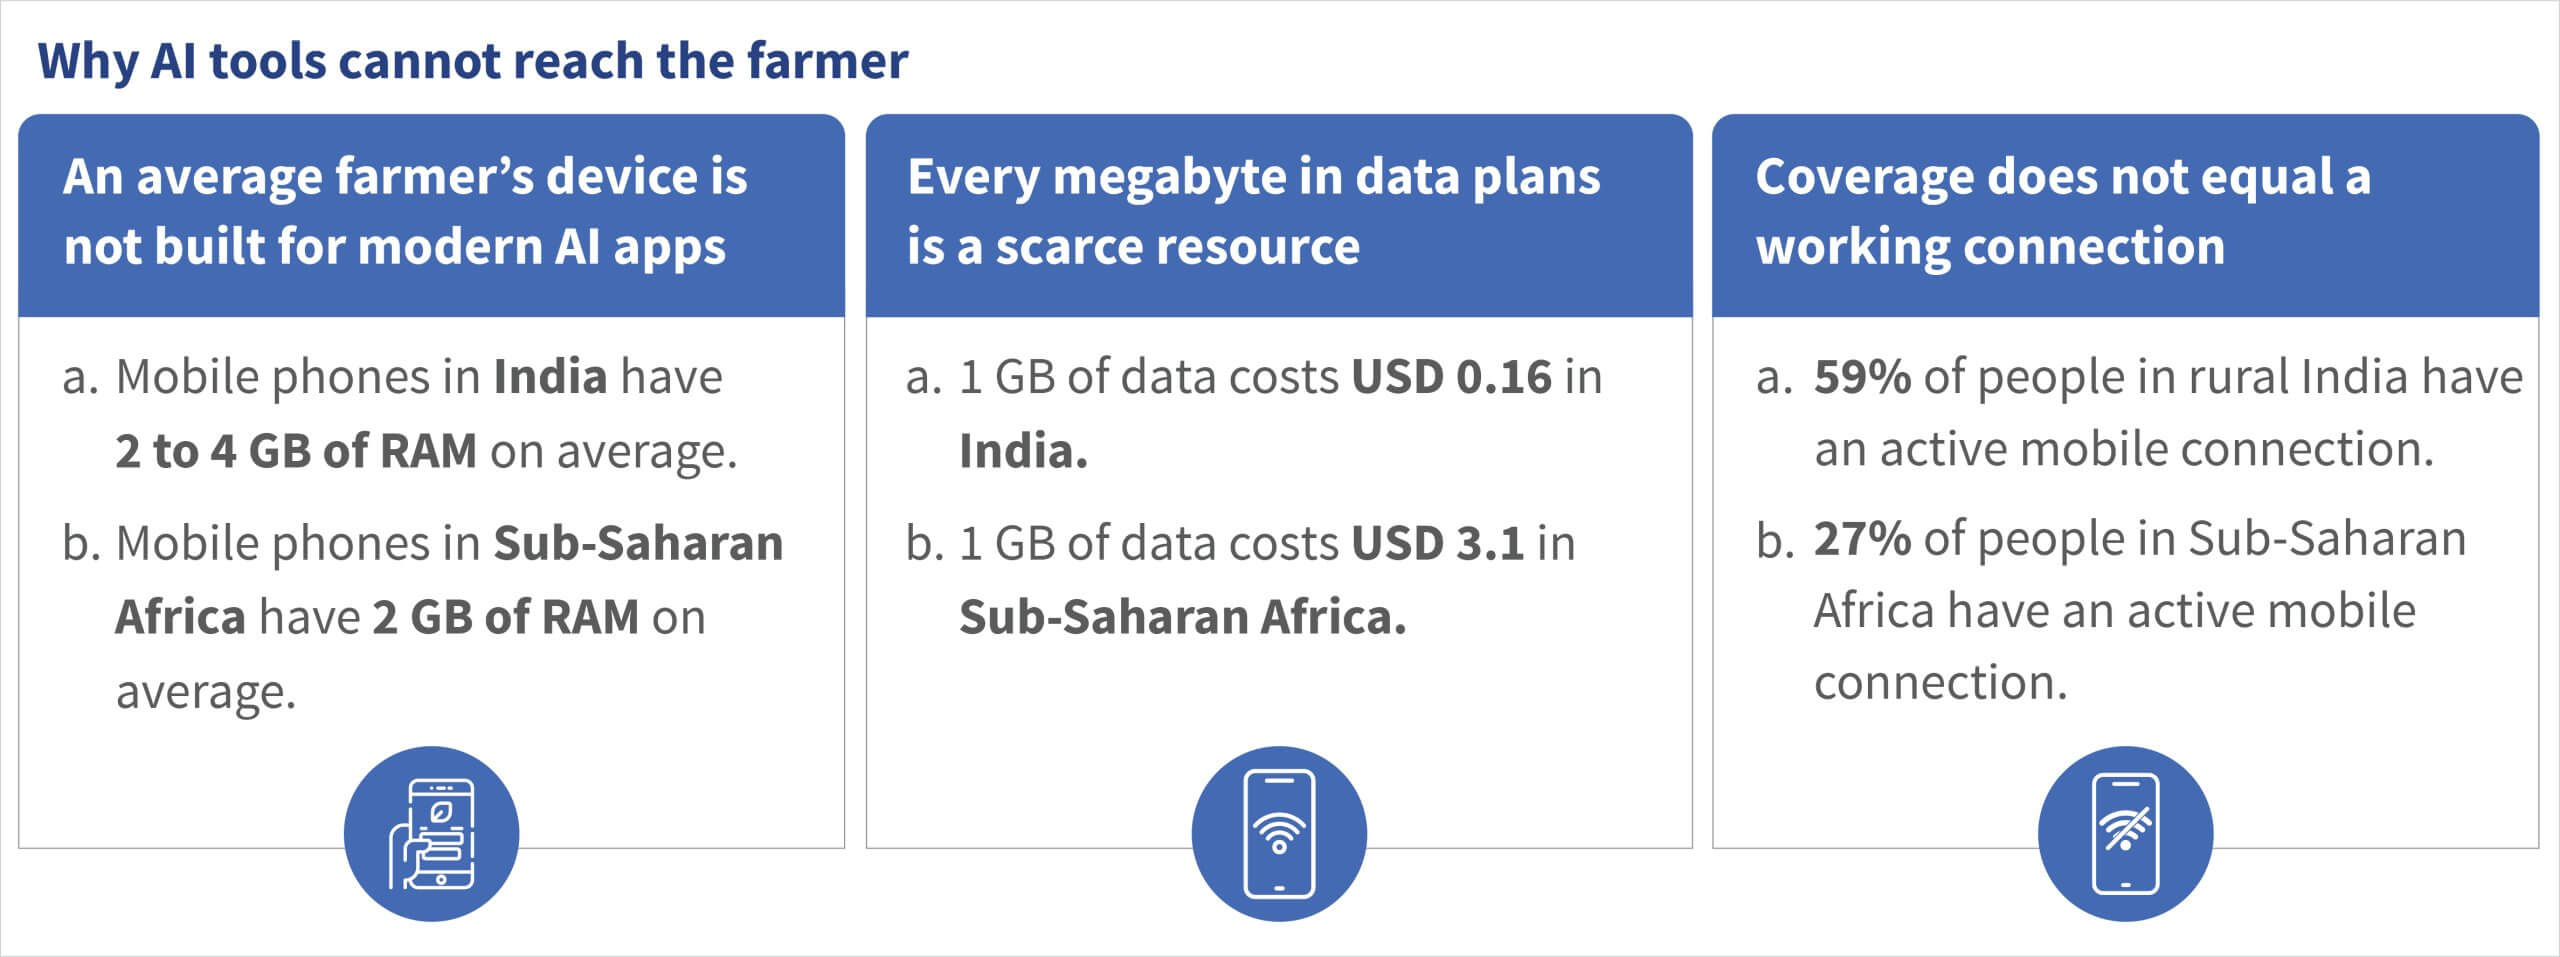
A modern AI app expects more from a smartphone than many farmers can provide. It requires processing power and available memory to run smoothly. Most farmers do not have that luxury. In India, the sub-USD 200 entry tier still dominates smartphone sales by volume. Low-cost devices typically have just 2 GB to 4 GB of random access memory (RAM), which is the phone’s short-term working memory. It affects how many apps can run smoothly at once.  

Infographic explaining why AI tools struggle to reach farmers: limited phone memory, costly data, and unreliable connectivity. It compares smartphone RAM, mobile data prices, and active mobile connection rates in India and Sub-Saharan Africa.

In Sub-Saharan Africa, the baseline is lower still. The GSM Association and African mobile operators have jointly proposed 2 GB of RAM as the minimum specification for an affordable 4G smartphone. The proposed specification sets a target below the current baseline. 

A 2 GB phone already runs a messaging app, a camera, and background sync, which leaves little room to hold a large upload in memory while a slow network catches up.  

Platforms designed and tested on newer devices can exclude the very farmers they seek to serve. The problem goes beyond what AI can do. The phone must also keep up long enough to deliver it. 

Data costs shape whether farmers use the service 


Data plans in South Asia look generous until you see what has to be shared with the allowance. For instance, Reliance Jio’s INR 349 (USD 3.66) plan, a standard package on India’s largest network, gives a subscriber 2 GB of data per day for 28 days. That 2 GB covers uploads and downloads, every app on the phone, and all other data use. A farmer must share the allowance across all digital needs, including crop-related questions.  

A geotagged, full-resolution photo from a modern camera uses roughly 3 MB to 6 MB per shot once GPS coordinates and device metadata are attached. A crop diagnosis requires the farmer to upload the photo and download the result. A single question can use a noticeable share of the farmer’s daily allowance.  

The numbers look very different across markets. Among the five cheapest mobile data markets in the world, two are in South Asia and the Pacific: Fiji and Cambodia. They have roughly USD 0.09 and USD 0.12 per GB, respectively, as per a study. India also has low mobile data costs, at USD 0.16 per GB.  

Sub-Saharan Africa is a different market. The same tracking study puts the regional average at USD 3.31 per GB, roughly 20 times the Indian rate. Zimbabwe alone reaches USD 43.75 per GB.  

So, the same advisory photo that costs a fraction of a rupee in India can cost real money in Harare, Zimbabwe. For a farmer working with a tight budget, that difference matters before AI even gets a chance to answer. 

Coverage does not guarantee a usable connection 


Coverage maps can make connectivity seem widely available. Yet, field data shows a different story. In India, 4G signal reaches 89% of villages. By early 2025, 5G had reached roughly 78% of villages as well.  Yet rural tele density, or the number of active mobile connections per 100 people, is only 59%, compared with 125% in urban areas. In plain terms, a village can have a strong signal on paper, while roughly four in 10 residents still have no working mobile connection to use it with. 

Even when a farmer has 4G, the connection may not perform well. Independent field tests of public 4G networks in rural agricultural settings rarely recorded speeds above 20 Mbps, and latency almost never fell below 100 milliseconds. Latency measures the delay between sending a request and getting a reply. Higher latency means longer upload times and a greater risk of failure.  

Sub-Saharan Africa shows the same gap on a larger scale. Roughly 85% of the population lives within reach of 3G or 4G broadband, but 63% remain offline inside that same coverage area. 

A weak or congested connection also worsens the cost problem. Mobile networks do not resume a broken upload at the point where it stopped. They restart it from the beginning. On a lossy connection, one retry can become five, and five can become 50 before a transfer succeeds. Each failed attempt uses more of the same data allowance. A photo that should cost a single debit against the day’s allowance. Network failures can make it use two or three times as much. The farmer pays for the network’s failure to deliver a reliable service. 

A platform that already confirms this 


Maharashtra’s own farmer advisory platform makes this point unintentionally. MahaVISTAAR-AI launched in May 2025 as a smartphone app. It delivers weather updates, market prices, and pest advisories to registered farmers across the state. Within a year, the state government added a voice-telephony layer to the same platform.  Farmers could reach it by phone without downloading an app, a smartphone, or an internet connection. This addition is more than a new feature. It shows that the original app-based design could not reach every farmer it was built to serve. The voice layer brings the service closer to the farmers described by the data above. 

What this means for AI in agriculture 


Device memory, data cost, and connection reliability are not separate problems. They compound each other and define the baseline condition of the market that these platforms seek to serve. These conditions are not an edge case that better infrastructure will eventually solve. A weak connection can delay an answer and increase the data cost of getting it. For farmers with a tight data budget, that cost can determine whether they use a tool or give up on it. AI in agriculture must account for how and where farmers can access the intelligence.  

A model that depends on a round trip to a well-provisioned server moves the constraint from the AI’s capability to the farmer’s access. Declaring a problem solved does not make that constraint disappear.  

For the farmer with the wilting maize leaf, access matters as much as AI capability. They need an answer on the phone they have, with the connection and data they can afford. 

MahaVISTAAR-AI has already found a partial answer through the phone network. The next blog in this series explores the next step. It examines what changes when the AI model itself runs on the device. This model can match the hardware farmers actually own and use, which has little or no network access. 

Blog part 2: “The intelligence belongs on the device”