Fish cross the border. Financing does not.

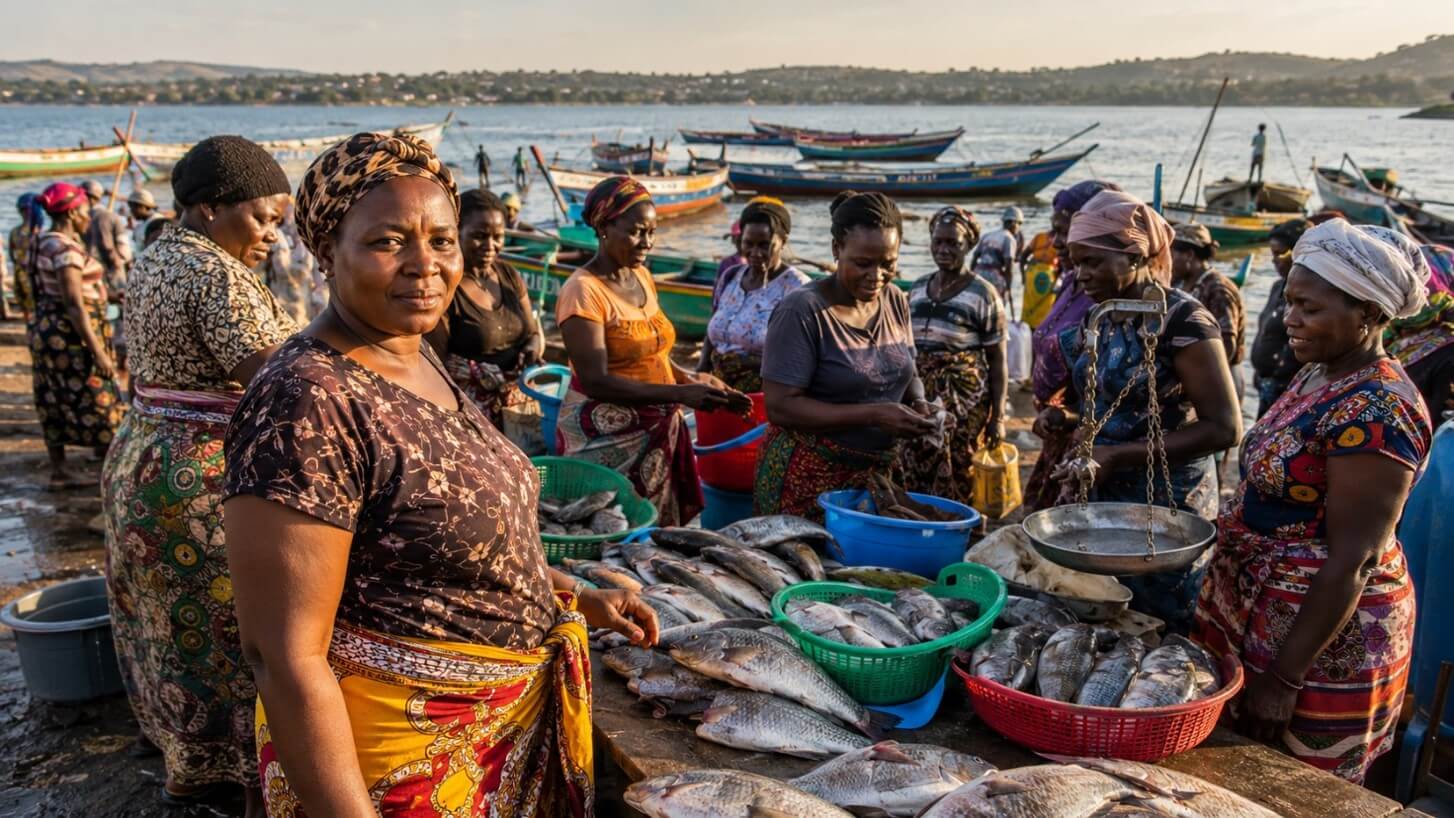
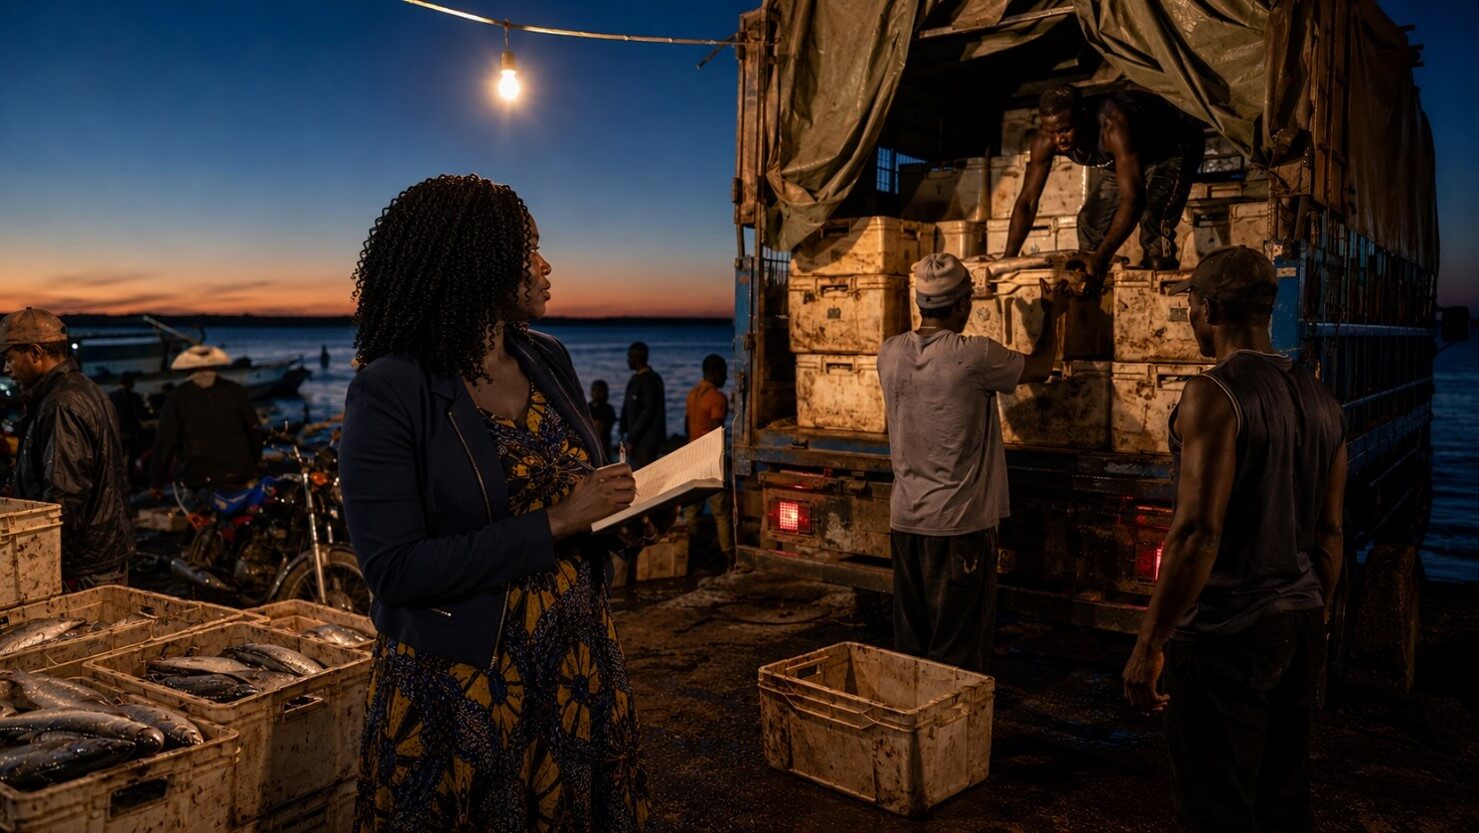
Adhis leaves Kalokol before 4 a.m. to buy sun-dried tilapia from fishers around Lake Turkana. She has pre-financed some of their catch. No single fisher has enough to fill her truck, so she builds the consignment one crate at a time before starting the long journey to regional markets. 

By sunrise over the Chalbi Desert, Adhis has secured the last tarpaulin and loaded the truck. The difficult part is only beginning. The fish will travel south and west through a corridor linking Kenya with Uganda, Rwanda, and the eastern Democratic Republic of the Congo (DRC). Markets such as Goma and Bukavu offer higher prices than those in Kenya. 

The 1,400 km journey crosses four countries and four currencies: Kenyan shillings, Ugandan shillings, Rwandan francs, and Congolese francs. It also passes through several border posts, each with its own documentary requirements, unofficial fees, and processing delays. Those delays can hold a refrigerated, and more often unrefrigerated, truck for hours in equatorial heat. 

Working capital may come from personal contacts or informal lenders. Adhis must often settle border-related costs and unexpected expenses immediately. 

Yet the commercial history behind these transactions remains fragmented. Supplier and buyer relationships, mobile-money transactions, consignment records, border crossings, and repayments are kept in separate records rather than forming a credit profile that a lender can assess across markets. 

The trade exists, yet formal finance has not matched this cross-border model at scale. 

The fish is already crossing 

Africa’s cross-border fish trade predates the African Continental Free Trade Area (AfCFTA). Fish already moves through established regional corridors as traders connect producing areas with markets with stronger demand. 

Women traders move omena from Lake Victoria into Uganda and Rwanda. Traders deliver Nile tilapia from Kenya to buyers deep in the DRC. Marine fish travel from Tanzania’s coast north to Nairobi and south to Mozambique. Informal supply chains carry fish along the Zambia-DRC copper belt corridor to mining communities in Lubumbashi and Kolwezi. In West Africa, Nigeria and Cameroon share one of the region’s highest-volume informal fish corridors, which rotating savings groups finance. 

The Women and Youth Economic Empowerment in Fisheries through Inclusive Market Access (WYEEFIMA) program operates within this reality. TradeMark Africa and the AfCFTA Secretariat implement the program in partnership with the Mastercard Foundation. MSC (MicroSave Consulting) supports access to finance across Kenya, Tanzania, Uganda, Nigeria, the DRC, and Zambia. 

Five financing gaps stand out. 

  1. Working capital that can move across markets

A trader operating across Kenya, Uganda, Rwanda, and the DRC may incur costs and receive payments in several currencies during one trading cycle. Exchange-rate movements, conversion costs, and payment timing can all affect margins. 

Corporate and commercial banks already offer multi-currency facilities, yet smaller fisheries traders often struggle to access them. Many manage liquidity through cash, mobile money, personal networks, or informal borrowing. 

Financial institutions can adapt working-capital products to businesses whose transactions span several markets. Transaction histories, repeat trading relationships, purchase records, and predictable routes can help lenders assess these businesses as cross-border traders rather than purely domestic borrowers. 

  1. Trade finance is suited to smaller transactions

A fish consignment sold to a known buyer across a border creates familiar trade-finance needs. The seller needs liquidity before payment arrives, and both parties face the risk of delay or non-payment. 

Letters of credit, guarantees, invoice finance, and similar instruments already address these needs in larger transactions. The gap lies in making suitable structures and ticket sizes accessible to smaller fisheries enterprises. 

Without such products, traders may finance purchases and transit costs themselves or through expensive informal credit. They carry much of the liquidity and payment risk personally. Confirmed buyers, repeat orders, invoices, consignment documents, and transaction histories can help formal lenders assess these transactions. 

  1. Insurance that reflects how fish move

Cross-border fish trade combines transport and product risk. Accidents, theft, breakdowns, border delays, and poor handling can reduce a consignment’s value before it reaches the buyer. 

Cargo and goods-in-transit insurance already exists, yet many smaller fisheries businesses struggle to access coverage that fits their operations. 

Tailored fisheries insurance is possible. GA Insurance launched Samaki Bima in August 2025, providing coverage designed around the risks fish farms face. 

This example suggests potential for similarly tailored products that cover cargo and transit risks for fisheries businesses moving perishable goods across borders. 

  1. A credit profile that can travel with the trader

A trader such as Adhis may already produce valuable information about her business, including mobile-money transactions, repeat buyers, supplier relationships, consignment records, and repayment behavior. 

These records sit across different systems and jurisdictions, making it difficult for a lender to form a consistent view of the business. 

Domestic transaction data also misses cross-border risks, which include currency movements, buyer default, border delays, spoilage, theft, and changes in documentation requirements. 

Bringing transaction histories, buyer relationships, route performance, and repayment records together could make the opportunity and its risks easier to assess. MSC’s work on meaningful financial inclusion for women similarly highlights the value of information that women already generate through their businesses, rather than relying only on conventional collateral. 

The challenge is to make these records consistent, consent-based, and usable across institutions and markets. 

  1. Finance for preservation and logistics

Cross-border fisheries trade depends on transport, storage, handling, and refrigeration, as required by the product. 

Leasing and asset finance can help businesses acquire trucks, cold rooms, insulated storage, and handling equipment without paying the full cost up front. Enterprises with limited formal credit histories may still struggle to access this finance. 

The financing structure must also reflect how the business earns money. Seasonal volumes, border delays, variable asset use, and irregular payment cycles can make standard monthly repayments a poor fit, even when the asset is commercially useful. 

Lenders must determine whether the asset supports a viable trade flow and generates sufficient cash for repayment. 

Making cross-border businesses visible to finance 

Under the WYEEFIMA program, MSC works with both fisheries enterprises and financial providers. 

For fisheries enterprises, this means strengthening the records lenders can assess, including transaction histories, consignment documents, buyer relationships, and cash flow records. For banks, microfinance institutions, savings and credit cooperatives (SACCOs), FinTechs, and insurers, it means understanding the fisheries value-chain economics and adapting products and risk assessment to these businesses. 

Better information does not remove risk. It helps lenders identify and price exposure to foreign-exchange movements, buyer default, transport disruption, product loss, and regulatory uncertainty. It can also prevent viable businesses from being excluded simply because domestic lending templates do not account for cross-border operations. 

Financial infrastructure is beginning to emerge 

Several building blocks are already in place. 

Afreximbank’s African Collaborative Transit Guarantee Scheme is designed to reduce the cost and friction of moving goods through several African customs territories. The Pan-African Payment and Settlement System (PAPSS) is building infrastructure for cross-border payments in African currencies. 

The next challenge is to extend this infrastructure to smaller fisheries enterprises and make it commercially viable. 

Financial institutions must recognize cross-border cash flows. Insurers and guarantors must cover transit and payment risks, while payment systems must reduce the cost and complexity of moving money between markets. Better records can help traders demonstrate the commercial history behind these transactions. 

Adhis will continue moving fish, whether the financial system catches up or not. Supporting her requires more than a loan. Payments, insurance, guarantees, portable records, and financing must move with the trade. The fish has already crossed the border; the opportunity is to ensure that the financial system can cross with it. 
The two-thirds opportunity: Where capital should flow

The previous blog in this series showed the scale of Kenya’s fisheries opportunity. In 2024, domestic production of 168,424 metric tons met about one-third of an estimated annual requirement of 510,000 metric tons. Data from MSC’s Women and Youth Economic Empowerment in Fisheries through Inclusive Market Access (WYEEFIMA) program also show the sector relies substantially on informal finance. 

This brings us to the question of where formal finance can work across Kenya’s fisheries value chain. As we will see, the answer may emerge from enterprises with viable markets, visible cash flows, and financing structures that match how they operate. 

Seven places where capital can work 

MSC’s work under the WYEEFIMA program points to seven areas where formal finance could support growth. 

  1. Working capital for fish-feed suppliers

Feed is among the highest operating costs in aquaculture. For cage and pond farmers, it can account for more than 60% of production costs. Moreover, Kenya depends partly on imported aquafeed, which exposes suppliers and producers to pressures related to working capital, inventory, and foreign exchange. 

For lenders, this creates a clear use case for working capital. Facilities linked to purchase orders, confirmed supply contracts, established sales histories, or recurring customer relationships could help suppliers stock ahead of demand. Financing suppliers can strengthen more than one enterprise. More reliable feed availability can ease a constraint for farmers further down the value chain. 

  1. Financing hatchery expansion

Aquaculture depends on a reliable supply of quality fingerlings, which places hatcheries near the start of the production cycle. WYEEFIMA data show that hatchery capital requirements range from relatively small working-capital needs to investments of more than KES 15 million (USD 117,238) for larger commercial operations. 

Hatcheries, therefore, need different products. Smaller businesses may need short-term finance for broodstock, feed, labor, and operating expenses. Larger hatcheries may require longer-term funding for tanks, pumps, water systems, equipment, and expansion. Meanwhile, lenders must assess whether production records, survival rates, customer demand, and repayment capacity support the requested finance. 

  1. Working capital for women aggregators and traders

Women play a major role in fish aggregation, processing, and retail. Yet, many have limited working capital and few productive assets that conventional lenders recognize as collateral. Their immediate need is often straightforward. They need enough liquidity to buy fish when supply is available, move it quickly, sell it, and return to the market for the next cycle. 

A cash-flow-based, collateral-light facility could assess these businesses through transaction histories, repeat supplier relationships, mobile money records, and established trading patterns, rather than relying only on fixed assets. 

Why does this matter? It matters because MSC’s WYEEFIMA market study found that informal borrowing remains an important source of working capital for most fish traders. Formal lenders could replace some of that high-cost, short-term borrowing with products matched to actual trading cycles. 

  1. Cold-chain infrastructure

Capital is also needed after fish leave the water. Recent research estimates losses at about 25% of production, which means post-harvest losses reduce the share of fish that reaches consumers in saleable condition. Cold storage, ice, handling equipment, and transport infrastructure are therefore vital opportunities to finance fisheries. 

For lenders, much of this is a use case of asset finance. Cold rooms, ice-making machines, insulated boxes, refrigerated transport, and related equipment can generate identifiable revenue when demand and use are sufficient. 

Yet, equipment is only part of the credit decision. Lenders must also understand throughput, energy costs, utilization, location, maintenance, and who will pay to use the infrastructure. The opportunity is strongest when a cold-chain asset serves an established fish-supply chain and a visible market. 

  1. Cluster finance for cage farming

In 2024, Kenya had approximately 5,975 fish cages in operation, which shows that cage aquaculture had already reached a meaningful scale. Further expansion may require more capital than individual microloans can provide. 

One option is cluster finance for farmers who share infrastructure, purchase feed collectively, coordinate market access, or sell through common off-takers. This structure can give lenders better visibility into production and transactions and allow farmers to share some operating costs. 

MSC’s pond-farming data also illustrate why repayment structures must follow biological cycles. A lender cannot finance a farmer whose revenue arrives only after harvest on the same schedule as a trader who turns stock every few days. Finance must therefore follow the production cycle instead of forcing the cycle to fit the loan. 

  1. Working capital and equipment for processors

Processors create value after fish are landed, yet many lack sufficient capital. Some need equipment, such as improved smoking kilns, drying racks, handling tools, or small cold-storage units. Others need working capital to buy fish when supply is available, before limited liquidity costs their business. 

Asset finance can support equipment with a useful life extending beyond a single production cycle. Short-term working capital can help processors purchase inputs and maintain throughput. Meanwhile, lenders should compare revenue and investment over consistent periods. Even so, these financing needs may be modest enough to fit within existing small and medium-sized enterprise (SME) portfolios. 

  1. Trade finance for fish-feed importers

Domestic fish-feed production will take time to expand. High-quality extruded feeds require formulation, manufacturing technology, quality control, and scale. Kenya’s experience illustrates these barriers. Take the Unga Group, for instance. One of the country’s long-established grain and animal-feed businesses, it expanded its feed business through a partnership with Nutreco to establish Tunga Nutrition Kenya and expand fish-feed production at its existing Nairobi plant. The partnership combined Unga’s local manufacturing and distribution network with Nutreco’s feed expertise and technology, increasing the capacity to produce fish feed locally. 

Meanwhile, importers and distributors must place bulk orders, clear consignments, carry inventory, and wait for payment from customers whose cash flows follow production cycles. 

These cash-flow gaps create a sizeable need for trade finance. Kenya imports about 7,000 tons of aquafeed annually, equivalent to roughly one-fifth of the country’s estimated annual feed demand of 34,000 tons. With published feed-cost benchmarks of about USD 850–950 per ton and more recent commercial feed prices averaging around USD 1.24 per kilogram, the value of inventory moving through this part of the value chain is substantial.  

Importers must finance bulk orders, freight, clearance, and inventory before recovering those costs through sales to distributors and farmers. Bank guarantees, letters of credit, and other trade-finance instruments could help established importers bridge that period, while lenders assess supplier reliability, currency exposure, inventory risk, off-take arrangements, and receivables. 

Fisheries finance requires a portfolio 

Across these seven use cases, fisheries finance requires a portfolio of distinct products. The mix should include short-term working capital for feed suppliers and traders, longer-tenor production finance for hatcheries and farmers, asset finance for processors and cold-chain businesses, and trade-finance instruments or guarantees for importers. 

Capital alone is unlikely to close the gap. A financial institution can design a suitable product and still struggle to find enterprises with reliable records or visible cash flows. A fisheries business may become more productive yet remain invisible to lenders that do not understand its operating cycle. The opportunity lies in matching the right capital and tenor to businesses that can use them productively. 

MSC’s analysis of youth entrepreneurship and financial inclusion reinforces this point: Finance and enterprise support must move together. Either one has limits without the other. 

The final blog in this series looks beyond Kenya. It examines how the African Continental Free Trade Area is expanding regional fisheries trade opportunities and what financial institutions need to finance cross-border flows. The answer to the opening question remains clear: Capital should go to enterprises with viable markets, visible cash flows, and financing structures that fit how they operate. 

The financing opportunity inside Kenya’s fish supply gap

Kenya’s fish market has a sizable supply gap. In 2024, the country produced 168,424 metric tons (MT) of fish, enough to meet about one-third of its estimated annual requirement of 510,000 MT. 

The remaining gap, roughly 342,000 MT, represents about two-thirds of the estimated demand. For lenders, that scale raises a crucial question: how much can viable domestic fisheries businesses supply, and what finance would help them grow? 

For financial institutions, that distinction matters. The opportunity extends beyond financing businesses that serve Kenya’s current production base. It also includes viable hatcheries, producers, input suppliers, traders, processors, and cold-chain businesses that can help close part of the supply gap. 

The two-thirds gap does not automatically define a bankable market. Affordability, consumer preferences, infrastructure, production constraints, and market access determine how much potential demand becomes actual sales. Still, the gap’s scale suggests that the financing opportunity could extend well beyond the businesses currently visible to formal lenders. 

As the first blog in this series argued, the gap in Africa’s USD 22 billion fisheries sector presents a development challenge and a potential commercial opportunity for financial institutions that understand how different parts of the value chain operate. 

A large gap between potential demand and domestic supply 

Kenya’s fish production is struggling to meet demand. Lake Victoria landings fell 29.9% between 2021 and 2024 amid overfishing and habitat degradation. 

Kenya currently fills part of its fish supply gap through imports, using foreign exchange on a protein source that it has the land, water, and workforce to produce domestically. 

How can domestic producers capture more of this demand? The answer depends on how much local supply can grow and what capital will enable that growth. 

Expanding domestic production could reduce import dependence and create opportunities throughout the fisheries value chain. 

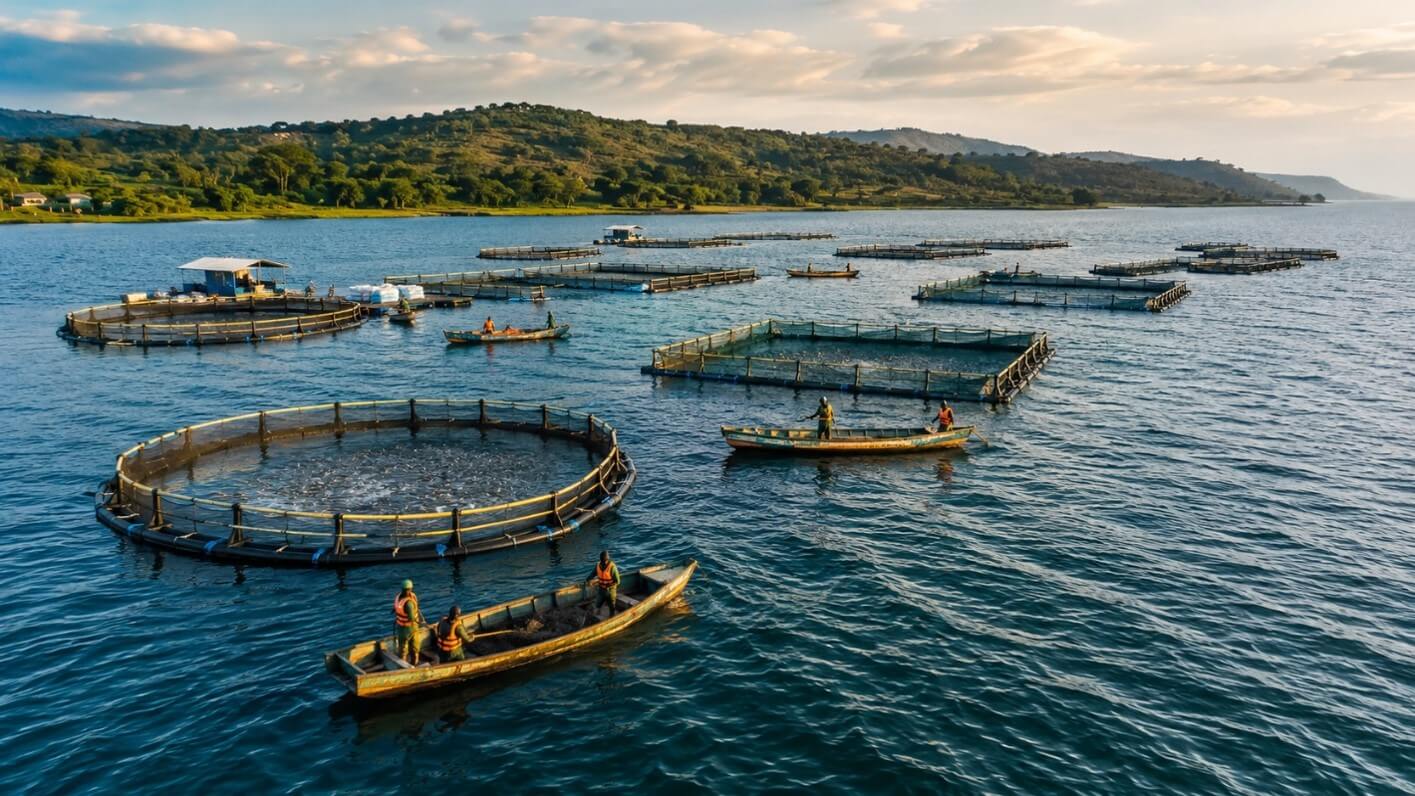
Cage farming in Lake Victoria shows how quickly managed production can reach meaningful scale. In 2024, Kenya had 5,975 operational cages managed by 634 farmers. These cages produced approximately 25,547 MT of fish and accounted for 76.4% of the country’s total aquaculture production of 33,423 MT. 

Scaling fisheries production involves far more than adding cages. Farmers need fingerlings and feed. Hatcheries need equipment and working capital. Traders need liquidity to purchase fish, while processors and distributors need cold-chain infrastructure. Each business has a distinct investment cycle, cash flow, and risk profile. 

Expansion, therefore, creates a series of distinct financing needs across the value chain. 

One value chain, very different capital needs 

MSC’s market study under the Women and Youth Economic Empowerment in Fisheries through Inclusive Market Access (WYEEFIMA) program, implemented by TradeMark Africa and the African Continental Free Trade Area (AfCFTA) Secretariat in partnership with the Mastercard Foundation program, illustrates this diversity. 

MSC’s research identifies nine fisheries value-chain actor profiles whose capital needs range from KES 1,833 (about USD 14) for a micro-retailer to KES 15.2 million (about USD 117,000) for a commercial hatchery. 

These differences matter for lenders. A lender cannot finance a trader seeking short-term working capital to purchase fish in the same way it finances a hatchery investing in equipment with a multi-year useful life. Similarly, a cage farmer’s repayment schedule must reflect an eight-month production cycle rather than the repayment pattern of a conventional retail business. 

Yet, formal finance reaches only a small share of these enterprises. MSC’s WYEEFIMA research estimates formal credit access at 9% among women and 14% among youth in Kenya’s fisheries sector. The study also found that some actor groups, including fish traders and seaweed farmers, rely heavily on informal finance. 

These enterprises have identifiable capital needs, yet formal lenders have not reached many of them. 

What early lending data shows 

Does additional finance help these enterprises generate enough income to justify greater lender interest? 

Early data from participating financial institutions (PFIs) in the WYEEFIMA program offer an encouraging signal. The analysis associates each additional unit of capital provided to fisheries enterprises with about 7.3% additional monthly enterprise income. The relationship became statistically significant within six months. 

In practical terms, every USD 1 of additional capital was associated with approximately USD 0.07 in additional monthly enterprise income. That equals about USD 0.88 over 12 months if the estimated monthly association persisted. 

Employment data points in the same direction. Between August 2025 and February 2026, 115 fisheries borrowers in the program generated 63 jobs, or about 0.55 jobs per borrower. Among borrowers who received loans above KES 100,000 (USD 771), the observed ratio was 1.33 jobs per borrower. 

The sample remains relatively small, so the pattern deserves further study as more lending data becomes available. Lenders often view larger fisheries loans primarily as a greater exposure risk. The WYEEFIMA data raises another question: could some fisheries enterprises productively absorb larger loans than lenders currently offer? 

Why lenders need a portfolio of fisheries products 

No single standardized product can close the gap. 

Closing part of Kenya’s supply gap requires different forms of finance across the value chain. Traders and input suppliers may need short-term working capital. Hatcheries and producers may need longer-tenor loans. Cold-chain operators and processors may need asset finance for equipment. Larger businesses may need trade finance or guarantees to purchase inputs at scale. 

Digital credit can meet some short-term liquidity needs. It cannot finance the full range of investments required to expand production and move more fish efficiently to market. 

For financial institutions, the opportunity lies in building a portfolio of financing solutions matched to how fisheries businesses operate. 

Yet this opportunity brings risks that lenders may struggle to assess or price. Some businesses have limited formal transaction histories or conventional collateral. Seasonal cash flows may also conflict with standard monthly repayment schedules. Capital alone cannot solve these problems. 

What can help lenders enter the sector? Better transaction data, alternative collateral approaches, guarantees where appropriate, and products structured around fisheries cash flows and production cycles can help lenders assess and manage early risks. 

Why the timing matters 

Kenya’s supply deficit is already evident, and pressure on wild-catch fisheries is increasing the importance of aquaculture and other forms of managed production. Cage farming demonstrates that aquaculture can produce at a meaningful scale when producers have suitable production systems, inputs, markets, and capital. 

Financial institutions that enter the sector now can begin building transaction histories, sector knowledge, underwriting experience, relationships with viable fisheries businesses, and portfolio data that later entrants will still need to acquire. 

Yet Kenya’s supply gap alone does not justify lending. A commercial case emerges when lenders identify businesses that can use capital productively, understand their cash flows, and structure finance around the risks they carry. 

WYEEFIMA’s early evidence suggests that such opportunities exist across the value chain and at widely different ticket sizes. For a financial institution sitting across the table from a fisheries client, the practical question is: where can it deploy capital productively, which enterprises are ready, and what products fit their operations? 

The third blog in this series examines that question through seven concrete financing use cases across the fisheries value chain. It explains how MSC works on both sides of the financing equation to make formal-sector entry viable. The lesson here is clear: Kenya’s supply gap becomes a financing opportunity only when lenders match the right capital to viable businesses across the value chain. 

Rethinking risk: A GEDSI-adjusted credit assessment tool for inclusive green finance in Indonesia

Access to finance remains a challenge for women-owned micro, small, and medium enterprises (MSMEs), especially those led by women with disabilities. Several factors limit their access to credit, such as inaccessible services, gaps in financial data, implicit bias, and unsuitable financial products.  

At the Financial Inclusion Week (FIW) 2026, MSC brought together representatives from Indonesia’s Financial Services Authority (OJK), the Terala Foundation, and KINETIK to explore how financial institutions can make green finance more inclusive.

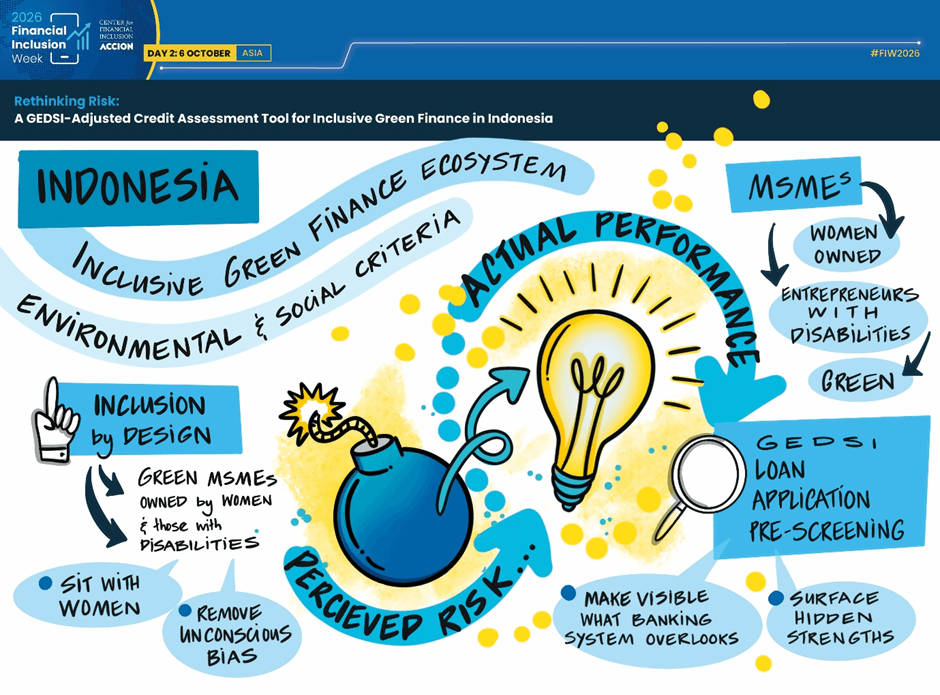
Conventional lending criteria may not capture a business’s full potential. As the illustration shows, inclusive green finance requires lenders to look beyond perceived risk and assess a business’s actual potential.

(Credit: Sonja Niederhumer’s visual illustration, developed during the session) 

Retnia Wulandari, Sustainable Finance Directorate Manager from OJK, highlighted the need to advance inclusive and green finance together. She emphasized the central role of the regulatory framework in achieving both objectives. Policies and initiatives, such as the Taxonomy for Sustainable Finance (TKBI) and gender equality, disability, and social inclusion (GEDSI)-related disclosures can support environmental and inclusion goals. 

Tien Mulyanthi, Founder and Executive Director of the Terala Foundation, highlighted the challenges women with disabilities face. She noted that exclusion can begin even before the loan application stage. Financial institutions must address accessibility barriers, data gaps, and differences in business circumstances from the outset.  

Pujiaryati Anggiasari, GEDSI Partnership Manager from KINETIK Hub, emphasized the importance of collaboration between development partners and national counterparts to turn initiatives into action. Government agencies, regulators, financial institutions, the private sector, civil society, organizations for persons with disabilities (OPDs), and development partners all have a role in addressing these interconnected barriers. 

Putu Monica Christy, GEDSI Sector Lead from MSC, introduced the Integrated Loan Application Initial Assessment Tool for GEDSI and Green Criteria. MSC developed the tool in collaboration with the Terala Foundation, with support from KINETIK. The tool offers financial service providers (FSPs) a low-barrier entry point to integrate GEDSI, disability inclusion, and green practice into loan assessments.  

As Indonesia advances its sustainable finance agenda, financial institutions can maintain rigorous lending standards and account for factors conventional approaches may overlook. 

You can access the recording of the session through the Center for Financial Inclusion YouTube Channel: https://www.youtube.com/@TheCFIchannel/playlists  

You can access the link to the Integrated Loan Application Initial Assessment Tool for GEDSI and Green Criteria: https://www.microsave.net/2026/07/13/integrated-gedsi-and-green-loan-assessment-for-inclusive-financing/  

The price and geography of financial absence

At Nyakwara beach in Kenya, Adhiambo starts her day before dawn. By mid-morning, she may have turned over stock worth thousands of shillings. By afternoon, a significant share of her earnings can go toward repaying a loan from an informal lender that charges 10% interest per day. On a simple, non-compounded basis, that is equivalent to 3,650% per annum. 

Adhiambo’s experience is not unique. MSC’s (MicroSave Consulting’s) fieldwork around Lake Victoria, conducted under the Women and Youth Economic Empowerment in Fisheries through Inclusive Market Access (WYEEFIMA) program, found many similar cases of fisheries businesses relying on expensive informal credit to finance their daily operations. 

The important question, then, is not simply why an informal lender can charge so much. It is why that lender may still be the most accessible source of working capital available to a fish trader. And why the phone in her pocket, which was supposed to make formal finance easier to access, may offer credit that is convenient, but still too costly, too small, or too short-term for the business she runs. 

Both are part of the price of financial absence. 

The geography of absence 

To understand what this absence looks like around Kenya’s Lake Victoria region, it helps to start with a place. Let us begin at Kendu Bay. 

Kendu Bay was once an important commercial center. Traders, shops, steamships connecting passengers and cargo to ports in Uganda and Tanzania, and the Kendu Show brought people and commerce to the town. Over time, Kendu’s affluence declined, Llake transport declined, road networks redirected activity, and much of the commercial center shifted elsewhere. 

Today, abandoned buildings with rusty iron-sheet roofs, collapsing stone walls, and empty streets mark the old commercial center. Fishers now use the old pier to watch the lake’s weather. Occasionally, a content creator turns up there to pose for a selfie. 


But Kendu Bay’s history matters for a different reason: financial absence cannot be easily explained by a lack of commerce.  

The same tension is visible across fisheries communities along Lake Victoria, which is a major source of fish and livelihoods. Yet, many businesses around its landing sites remain far from financial institutions. 

In 2024, fishers on Lake Victoria landed 67,575 metric tons of fish. Along Kenya’s approximately 550 km of shoreline, hundreds of landing beaches support fishers, traders, processors, transporters, and other businesses whose incomes depend on moving fish from the lake to consumers. 

A few examples suffice. Consider Sindo, a landing site and trading center in the Lake Victoria region which has no bank branch, Savings and Credit Cooperative office, or microfinance desk. Nearby island communities such as Rusinga, Mfangano, and Remba face even greater geographic constraints because access depends on boat or ferry transport. For fisheries businesses along this corridor, reaching a commercial bank branch means traveling to Mbita or Homa Bay, paying for transport costs, and losing hours that would otherwise be spent trading. 

County-level financial inclusion statistics may classify these communities as “served.” On the ground, their experience tells a different story. Even where economic activity is vibrant, access to formal finance often stops well short of the beach. 

Physical distance is only part of the problem. 

A fish trader may have no formal employment record, limited conventional collateral, or little transaction history a bank recognizes. She may also doubt whether a financial institution understands how her business works. 

This matters because the financing challenge is substantial. Ironically, discussions about closing Africa’s estimated USD 12 billion annual aquaculture financing gap often focus on product design, loan sizes, repayment schedules, collateral, and tenor. Those questions matter. Yet another comes first: where would a fish trader in Sindo or Nyakwara access such a product, even if it existed? 

MSC’s fieldwork under the WYEEFIMA program reveals the same disconnect: the fish, traders, and commercial activity are present, while suitable financial services are often absent. 

Many communities around Lake Victoria have no nearby physical financial presence. This absence also weakens trust. MSC’s research on cash-in/cash-out agents shows that access alone does not determine whether customers use financial services. Convenience, trust, and the quality of human support also shape adoption and continued use. A mobile app alone may not give a fish trader with little experience of formal finance the confidence or context she needs. 

However, digital credit has helped bridge some of this gap.  

Affordable device financing and fast approvals based on mobile money transaction histories have made digital credit one of the first formal financial services that many Kenyan households encounter. By May 2026, 252 licensed digital credit providers had issued 8.37 million loans worth KES 150.56 billion (USD 1.16 billion). 

Yet greater access has not always brought greater affordability, especially when borrowers repeatedly use short-term digital credit. For example, M-Shwari, a mobile savings and loan service offered through M-PESA, charges a 7.5% loan fee plus 1.5% excise duty for a one-month loan. In contrast, Fuliza, M-PESA’s overdraft service for completing transactions when a customer has insufficient funds, charges an access fee and tiered daily charges that vary with the amount borrowed and the repayment period.  

Cost is only one part of the mismatch. Many fisheries businesses need more capital and longer repayment periods than standard mobile credit offers. A wild-catch business with an annual turnover of KES 600,000 (USD 4,618) needs working capital aligned with its trading cycle. An omena trader may need credit through a three-week lean season. A pond farmer may need finance for an eight-month production cycle, allowing fish to reach harvest before repayments peak. 

Larger enterprises have different needs. Hatcheries and aquaculture small and medium-sized enterprises (SMEs) need structured working capital, asset finance, or trade finance, while processors may need cold-chain equipment. A small, short-term, standardized mobile loan cannot meet all these needs. 

This points to a broader challenge: access alone is not enough.  

Digital channels can reduce distance. Yet lenders must understand fisheries businesses’ seasonality, production cycles, price and input risks, trading relationships, cash flows, and limited conventional collateral before they can provide higher-value products. These include working-capital loans, asset finance, insurance, and longer-term production finance. 

The challenge combines access and fit. MSC’s research on gender-intelligent banking in Kenya reaches a similar conclusion: products must reflect how customers earn, borrow, and manage money. 

Lenders and their partners can close this product and distribution gap through trusted local intermediaries, better use of transaction data, and financial products that reflect fisheries cash flows and production cycles. The commercial opportunity is clear: these businesses already generate revenue and pay for capital, often at considerable cost, yet formal finance still underserves them. 

The second blog in this series will examine the size of that opportunity and where capital can go. For now, Adhiambo’s experience offers a clear answer to the opening question: access must combine reach, trust, and financial fit. Without all three, formal finance remains absent from the businesses it is meant to serve. 

Lowering the cost of serving clients with shared AI infrastructure

Lenders, insurers, and agricultural businesses in the same country each pay to build similar AI foundations. Building the shared parts once would help them serve smallholder farmers and small businesses better and at lower cost, while each retains control of its clients, data, and decisions. 

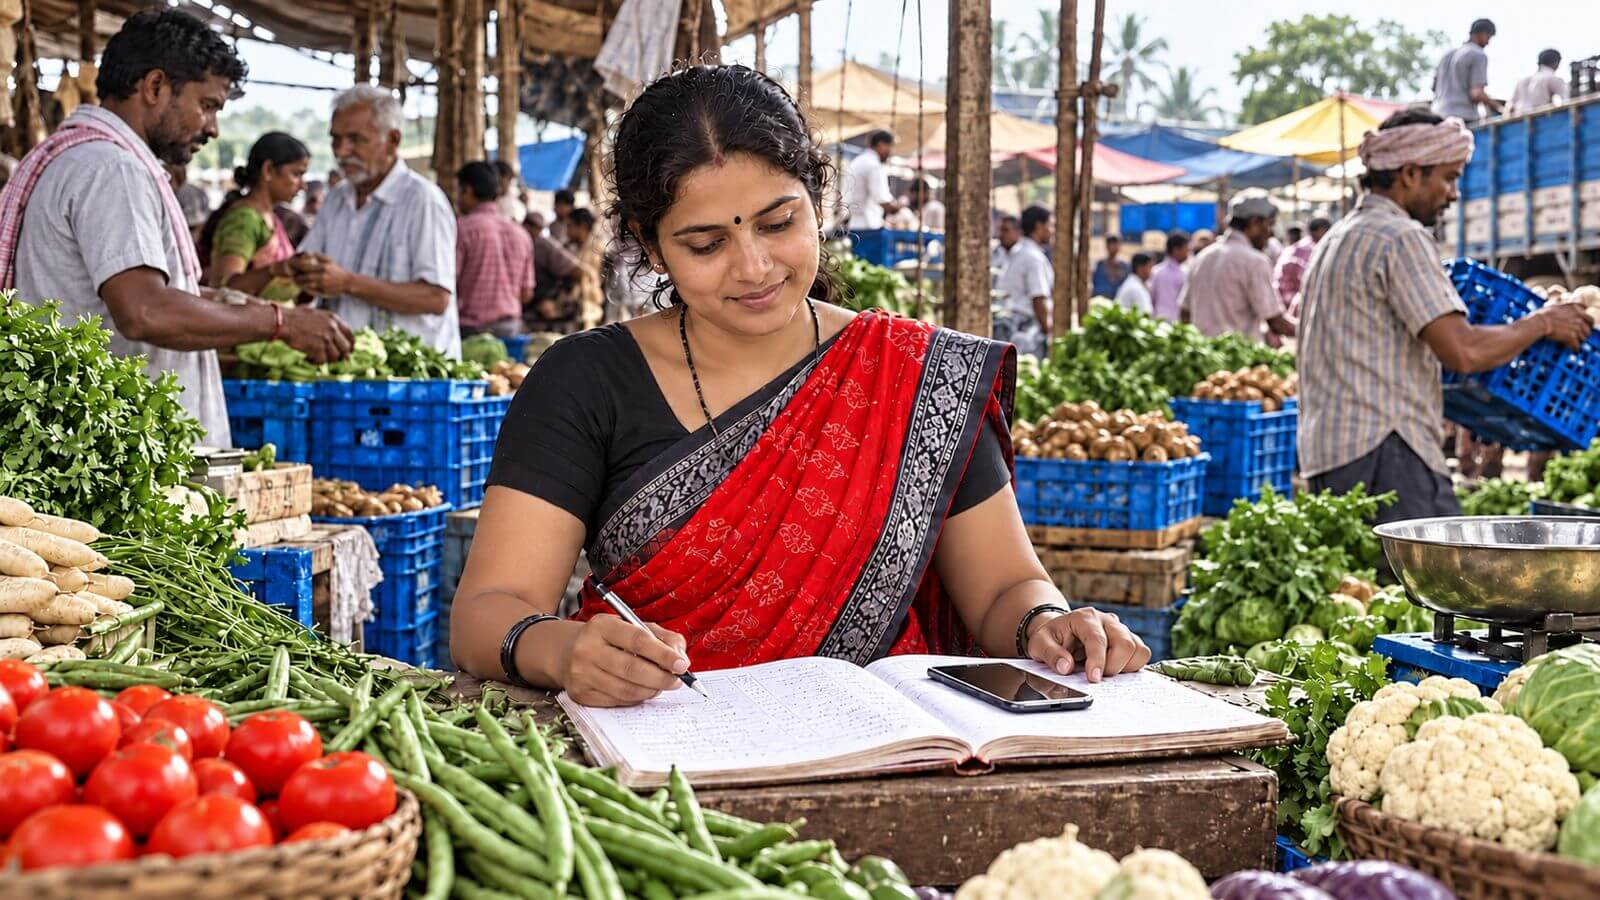
Take Malti, a vegetable seller in a market town in India. She needs a small loan to buy stock before the busy season. She keeps her accounts in a notebook, is paid mostly in cash, and speaks a language her lender’s systems cannot read. Field visits to serve her add costs that the interest on her loan cannot cover, so she is turned down or is offered credit on tougher terms. 

A dairy farmer in Kenya, a coffee grower in Colombia, and a sari-sari store owner in the Philippines face the same barrier. Artificial intelligence (AI) can lower it by reading a handwritten ledger from a photo, answering in local languages, and giving the lender a clearer view of risk. Doing this well takes four kinds of AI working together, and no single supplier offers all four. We propose building that foundation once, as an open commons, and seek partners to fund it. 

AI can help clients run, buy, and sell better. 

Only 56% of adults in low- and middle-income countries can raise emergency funds within 30 days, as per the Global Findex 2025, and small businesses in emerging markets face a USD 5.7 trillion credit gap (SME Finance Forum and IFC, 2019 estimate). Beyond the loan decision, AI can help these businesses run better, buy better, and sell better by finding cheaper suppliers, a government incentive they qualify for, and new buyers. The test of every tool is whether the client’s financial health, income, and resilience improve. 

A provider needs four AI capabilities at the same time. 

Four capabilities must work together to serve  Malti’s well and cost-effectively. 

  1. General reasoning, for informed decisions: The client gets coaching on running her business, and clear answers to her questions. The provider’s staff process applications and get answers in seconds. 
  2. Local language and documents, to overcome language barriers: The client gets advice in her own language, by text or by voice, even on a basic phone with a weak signal. The provider reads a handwritten form without retyping it. 
  3. Domain analysis, for practical insights: Smaller, domain-specific models analyze supply chains, market prices, or rainfall and soil. The client learns what to plant, and when and where to sell. The provider sees risk more clearly. 
  4. Traceable decisions, for transparency and accountability: The client gets a reason she can understand, and a way to challenge a decision she thinks is wrong. The provider keeps a record that its supervisor can audit. 

No single supplier offers all four. The strongest reasoning tools are rented from global companies, run outside most of these countries, and work best in English. Local language tools are improving, with regional efforts, such as Sarvam in India, SEA-LION across Southeast Asia, and Latam-GPT from Chile. Yet, as MSC’s fieldwork shows, reading handwriting in a local script or answering by voice in most African languages is not yet reliable. Domain-specific models or “small AI” models built for a particular purpose need local data. Traceable decisions require the provider to retain the evidence, rules, and model versions behind a decision, so a client or regulator can understand how it was reached.  

Few providers have the staff to run and maintain these systems internally. 

One trusted layer allows a provider to mix suppliers and keep control. 

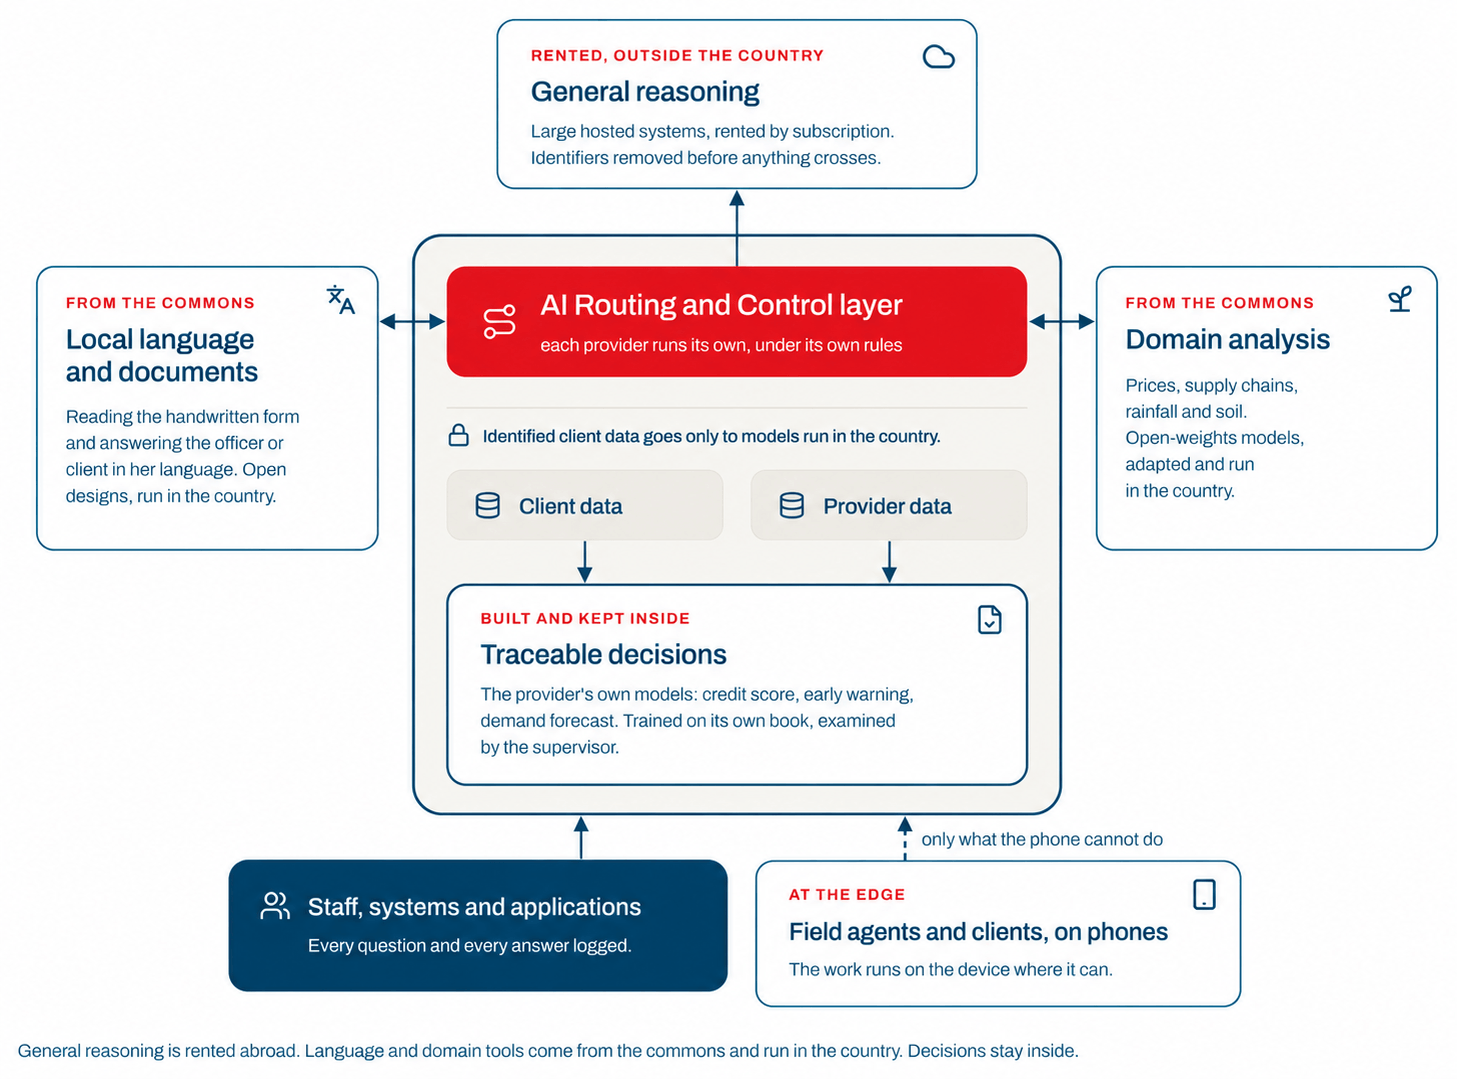
Our design places an AI Routing and Control layer between the provider and every AI system it uses, and each provider runs its own. Think of it as a switchboard with a rulebook. Every call from staff, systems, and applications passes through it, as does every request from a phone that the device cannot handle. For each request, the layer decides two things: What the AI system may see, and what it may do. 

When a model needs context, such as a client’s record, the provider’s credit policy, or a scanned form, the layer retrieves it under the provider’s permissions. Identified client data goes only to models running in the country, and identifiers are removed before anything goes abroad. When a model needs to act, such as checking a balance or pulling a bureau score, it does so through the layer, never directly. The provider writes the rules in terms its supervisor can read, and the layer logs every question, answer, and action. 

Models used for business decisions, such as credit scoring, stay inside the provider’s environment and feed its own decision engines. On the phones of agents and clients, the work runs on the device where it can, even offline, as MSC’s x-VOX platform already does. Only what the device cannot do reaches the layer. 

Diagram of an AI architecture where routing controls locally run language and domain models, keeps identifiable client and provider data in-country, records traceable decisions, and uses rented overseas systems only for anonymized general reasoning.

Because every call passes through one place, the provider can change suppliers as technology, prices, and regulations change, as long as the new system’s license allows commercial use, which some open models, such as InkubaLM, do not. While building this design is one thing, running it is where many providers will struggle. 

Build the shared parts once. 

Take 12 financial service providers in one country. They share a supervisor, an identity system, a payment network, and a set of languages, yet each builds the same connections, language tools, and tests alone. Each still funds what it competes on from its own balance sheet, and without peer evidence of a return, most boards wait. Little outside capital fills the gap. As of September 2026, financial inclusion and agriculture received USD 445 million across 12 countries, of the USD 90 billion in AI capital tracked by the Accendo Capital Flows Map in emerging markets. That is half a cent in every dollar, and nearly all of it went to single firms. 

We propose building an open commons, held by a nonprofit, which publishes three things: An open design for the layer, local-language tools, and domain-specific models with open weights that anyone can inspect. Each provider implements them locally on its own systems, under its own rules, and adapts them to its own market. Providers gain lower costs, peer results before they commit, and common standards that let them change vendors, while each remains accountable to its supervisor.  

Grants would build the commons, and member fees would maintain it. We seek funding partners who back shared infrastructure, and want to hear from providers, vendors, and supervisors who see the problem differently. 

Malti the vegetable seller will never see the AI Routing & Control layer. She will see a lender who can read her notebook, answer her in her own language, and offer terms that work for her business. A shared foundation makes that affordable for every provider in her country. 

This is the first of four parts. Part two goes deeper into the architecture: The walled, gated garden that sets what a provider owns and what it rents, how the layer works on devices, and how the commons is governed and funded. Part three looks at the risks, including shared models that fail together, and how the design answers them. Part four sets out named asks to funders, supervisors, and providers, and a first group of providers in one country. 

This blog is part one of a four-part series by Accendo Associates and MSC (MicroSave Consulting). 

More to come.