From just-in-time to smart payments: A case for innovations in Centrally Sponsored Schemes in India

Context

The efficacy of transfers from higher to the lower tiers of any government depends on the underlying fund disbursement system. Sample this—the Government of India, as per the budget estimates of 2024-25, plans to transfer funds worth USD 266 billion or ~7% of India’s GDP, to states. This includes devolution of states’ share, grants or loans, and releases under Centrally Sponsored Schemes (CSS). The level of sophistication of these systems have a huge bearing on the nation’s ability to spend and spend well.

On 13th July 2023, the Department of Expenditure (DoE) issued a memorandum to implement the SNA-SPARSH mechanism to ensure the “just-in-time” (JIT) release of funds allocated to the CSS through the RBI’s e-Kuber platform. It builds upon the significant gains of the Scheme Nodal Agency (SNA) system’s implementation in July 2021. This blog post highlights the journey, challenges, and innovations in CSS funding. It focuses mainly on the SNA-SPARSH model and its implications for efficient fund release and payment processing.

SNA-SPARSH’s implementation in India represents a significant milestone in the government payments ecosystem, where the holy grail is to achieve JIT payments. As the name suggests, JIT payments would eliminate the gap between the actual physical event, that is, the work for which the payment is due, and the fiscal event. In this context, the fiscal event is the outward movement of money from the consolidated funds to the end beneficiary—a citizen, a business, or other government bodies.

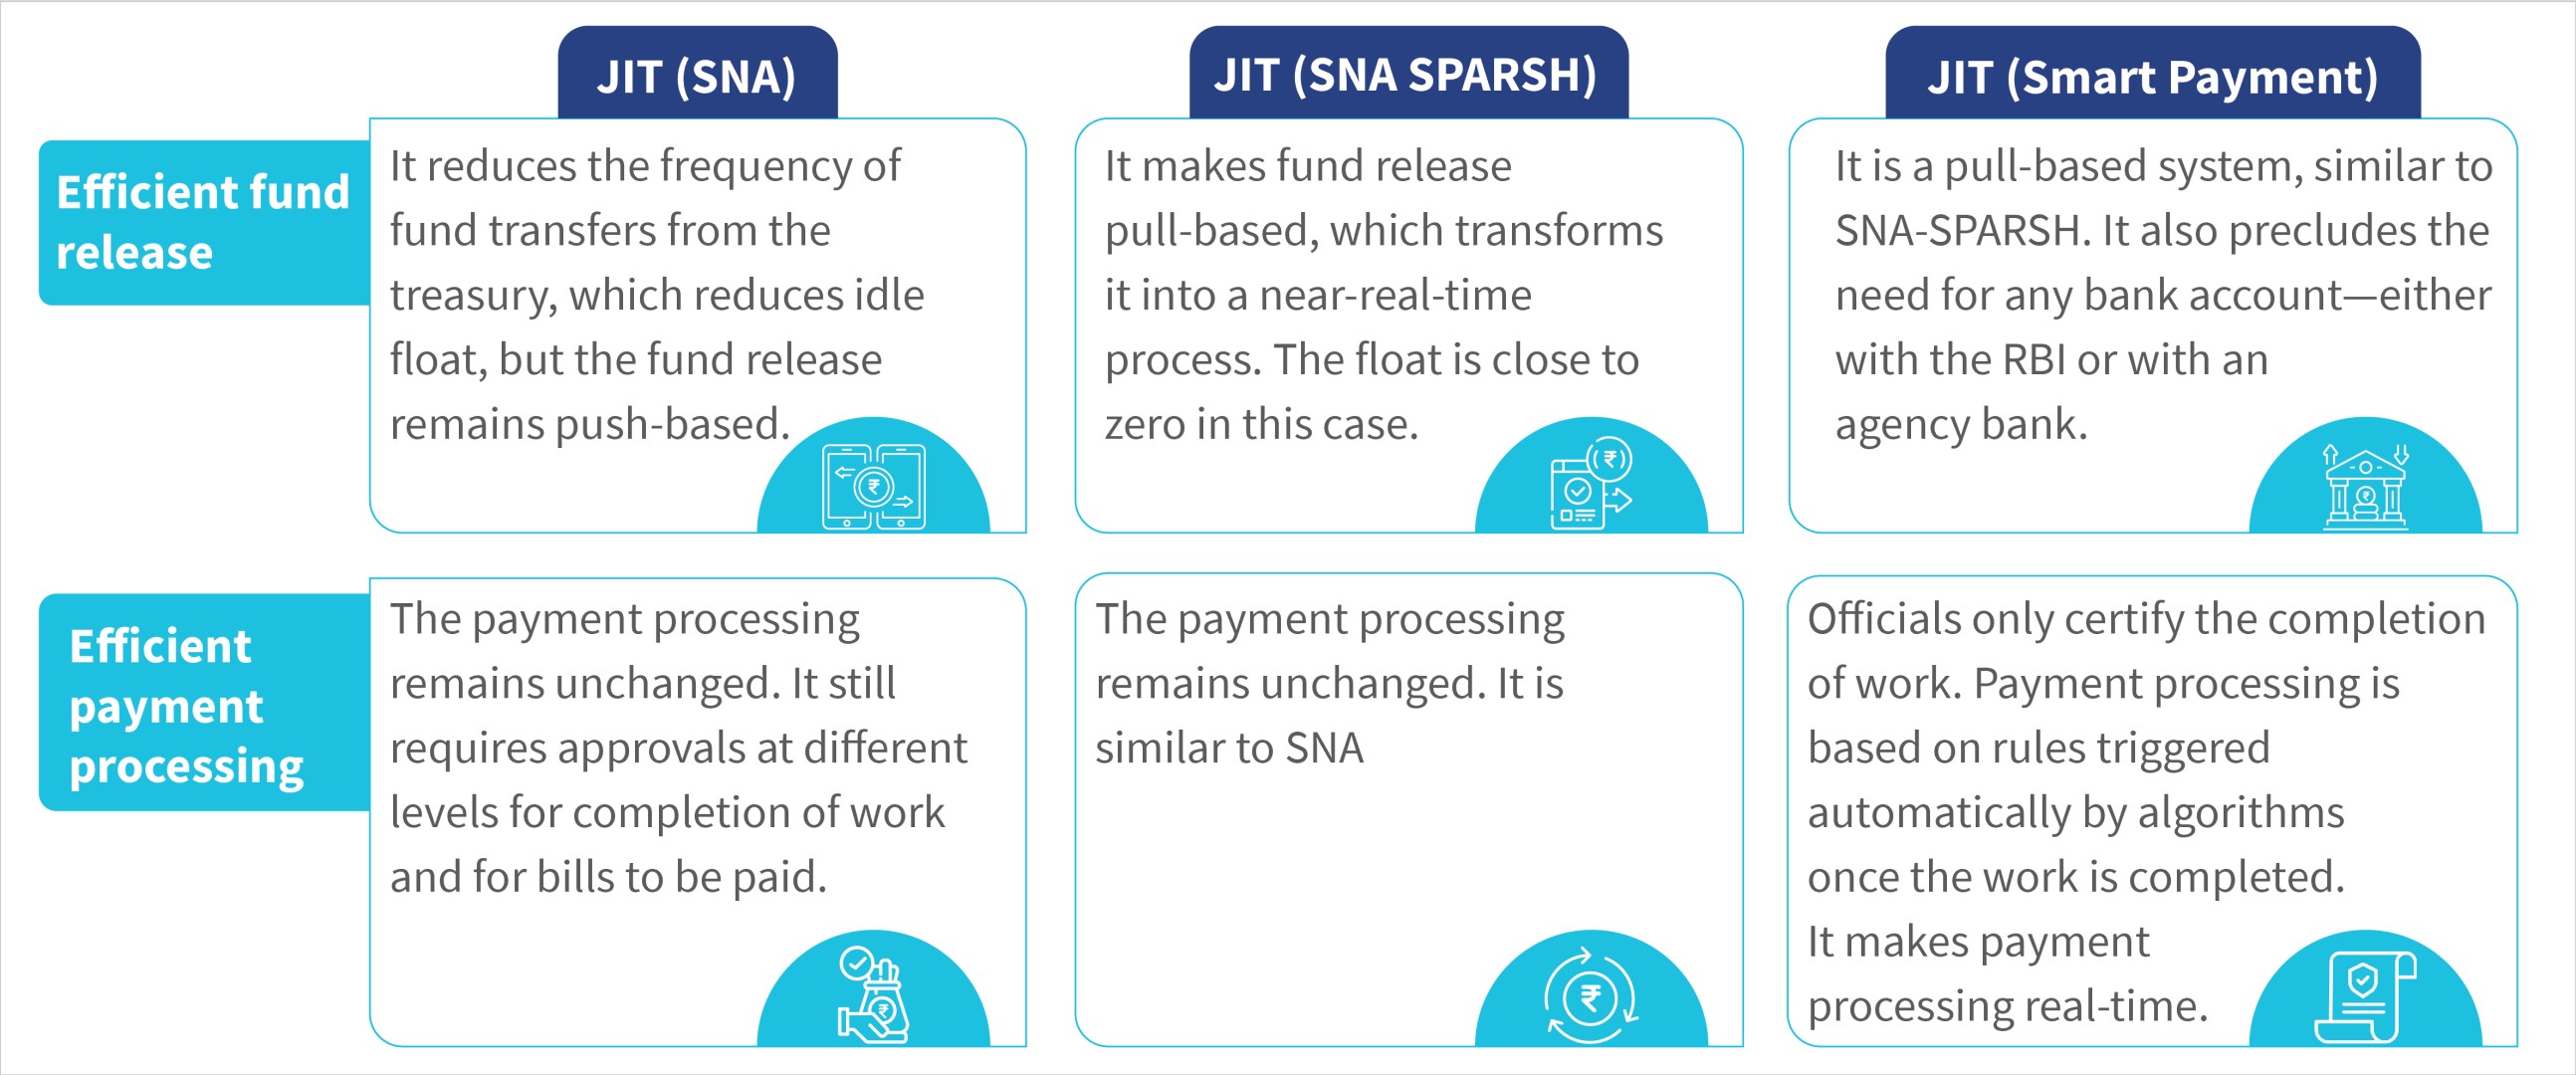
An implicit assumption in the government fund flow is that money will be pushed from one level to another, but SNA SPARSH inverts this assumption. It allows an agency that makes expenditures to pull funds up to the sanctioned limit when needed. With this, SNA SPARSH pushes the envelope toward smart payments, not just JIT. Operationally, the smart payment system will have two core attributes:

  • Efficient fund release: “pulling” funds from the treasury and passing them on directly to the beneficiary’s bank account;
  • Efficient payment processing: pulling funds in “real-time,” that is, just when payment for the work is due, based on rules triggered through algorithms.

The table below compares the three evolving versions of JIT on these two attributes.
At the root of this ambition for JIT payments is to enhance the state’s capacity to make expenditures effective and efficient. While the budgetary allocations to social sectors by the governments have slowly increased, available evidence suggests budgets remain unspent. Even with spent budgets, the achievement of outcomes remains low.

CSS accounts for a substantial portion of the central government’s budget, as per the interim budget for FY’25, at INR 5.02 lakh crores (~USD 60 billion), CSSs’ share is about 51% of the total transfers committed by the central government to the states. Thus, the deployment of JIT for CSS can potentially bring significant gains to optimize fund utilization and improve outcomes in the public sector.

A brief history of (just in) time

Over any given year, the CSS would be funded via a cascading fund transfer mechanism. Since the money moved from one agency to another, it led to funds in government bank accounts that sat idle for months or years before they needed to be spent.

The SNA was introduced to consolidate banking arrangements, reduce float, and enhance transparency in fund utilization. It has successfully integrated treasury systems across states and union territories, significantly reduced the number of government accounts, and provided real-time insights into fund releases and expenditures. It tackled challenges, such as unspent balances, cash shortages in some implementing agencies, and inefficient fund release strategies.

The quarterly release of funds and contingent additional releases based on utilization have helped reduce float and prevent the accumulation of unspent balances. India’s Finance Minister highlighted estimated annual savings of USD 1.2 billion from the SNA reforms. The SNA model successfully consolidated funds, improved transparency, and addressed various challenges in the fund release process.

SPARSH—the “pull” to complete the fund release

Under the SNA, the funds are still being “pushed,” albeit with fewer intermediate halts, in shorter bursts, and with a good view of where they are at any given time. The gap between the fiscal and physical events has also been reduced but not eliminated.

However, SPARSH marks a transition from a credit push (a-priori release of funds to various implementing agencies) to a debit pull-based fund transfer system in which a debit to the central pool is triggered only when implementing agencies issue payment instructions on the system. By design, SNA-SPARSH can “pull” funds in real time to the end beneficiary’s account, which takes it closer to a smart payment system. These design features are:

  1. Integrated framework of PFMS, the state’s treasury or financial management system and the RBI’s e-Kuber platform that enables seamless flow of information across three systems;
  2. Ability to onboard CSS, SNA, and implementing agencies on the platform—the last two via IFMS;
  3. Creation of CSS-wise sanction orders for each state at the beginning of a financial year.

Under SPARSH, the eventual release of funds into the beneficiary’s bank account is triggered once the SNA or implementing agency generates the payment files. However, clarity is absent in the time gap between the generation of payment files and the physical event—the moment the work or the payment milestone is achieved in the field. When we revisit the holy grail of just-in-time payments, we find pulling of funds is not in “real time.” This does not qualify it as a just-in-time system since challenges in payment processing persist at the program implementation level.

Cometh the hour, cometh the smart payments

What is needed in this context is a payments processing system that can process payments, that is, generate payment orders automatically upon fulfillment of payment conditions for payees, such as vendors and citizens. Further, it should “talk” to the IFMS system to permit “straight-through processing” of invoices without manual intervention. In other words, we recommend a system that generates the payment files that SNA or implementing agencies can feed into the state IFMS.

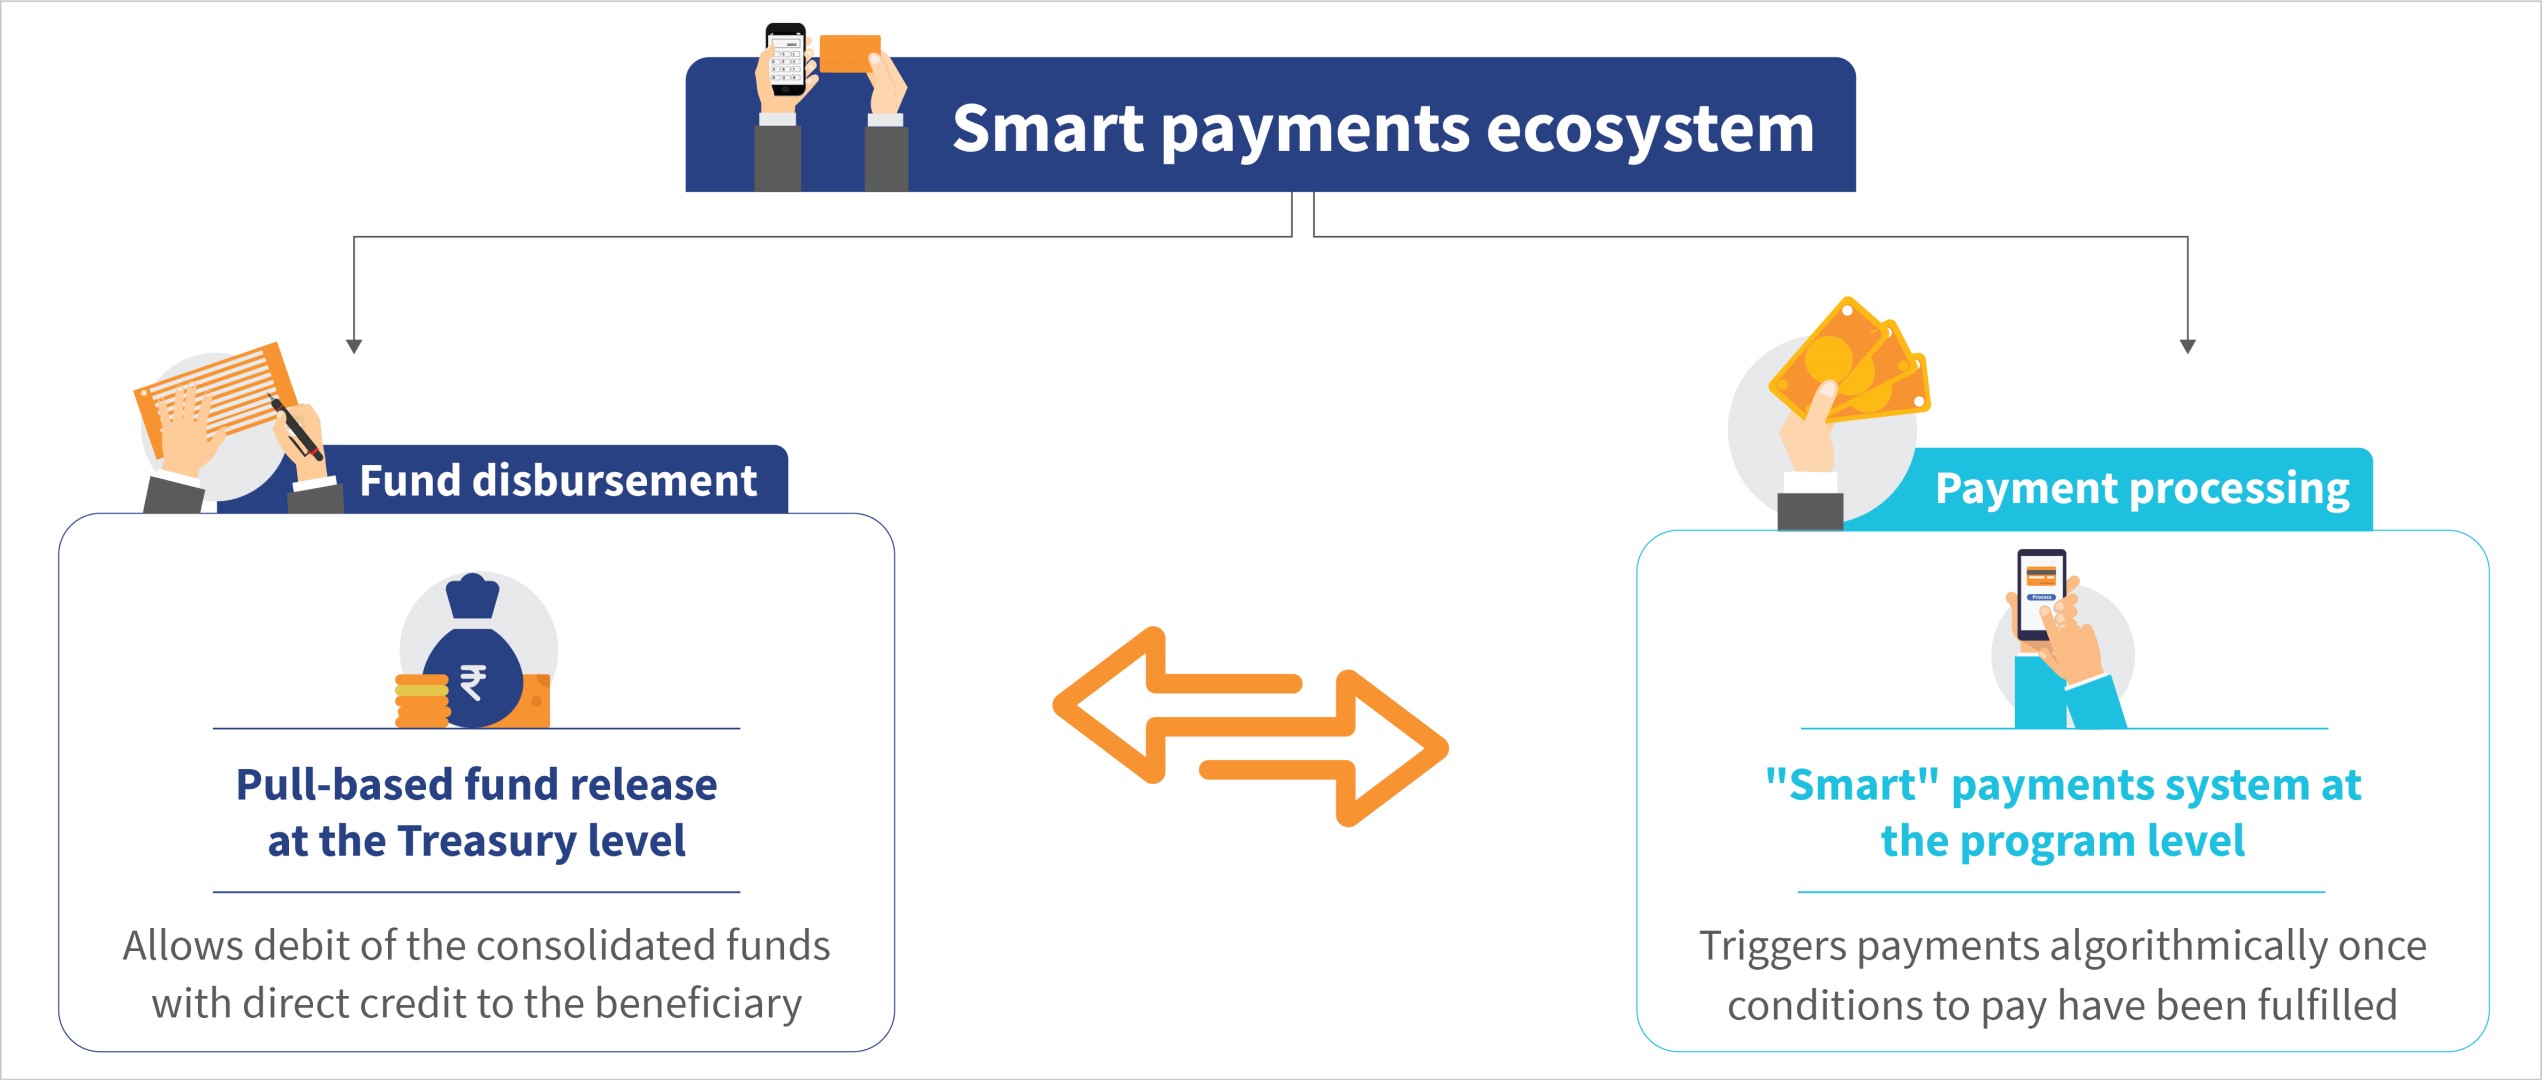
When integrated with a pull-based fund transfer system like SPARSH, such a “smart” payments system creates a “smart payments ecosystem” that meets both the conditions of pull-based fund disbursement and the real-time processing of payments. The figure below shows this in detail. SPARSH’s pull-based fund transfer functionalities can be further improved by using a virtual treasury single account (VTSA), which would also eliminate the need to park funds it in any bank account—either with the RBI or an agency bank.
One such smart payments ecosystem is currently being implemented in Odisha. The Government of Odisha launched the MUKTA (MUkhyamantri Karma Tatpar Abhiyan) program to tackle job vulnerability that resulted from the COVID-19 pandemic. MUKTA encountered challenges, such as delays in claim settlement of wage-seekers and SHGs, idle parking of project funds, and ineffective project management.

MSC designed the “smart payments ecosystem” based on our work with the state’s Finance Department since early 2020. We designed a VTSA-based JIT funding system and a smart payments system, “MUKTASoft,” for the Housing & Urban Development Department.

The solution has enabled the transition from a “push-based” to a “pull-based” fund transfer system for beneficiaries, including wage-seekers, SHGs, and material vendors. Under it, the implementing agencies (urban local bodies in the case of MUKTA), pull funds from the state’s consolidated fund directly into the end beneficiary’s bank account in real time when a payment milestone is completed. The solution also incorporates autonomous rule-based processing of payments, which significantly streamlines the process and reduces the burden on officials.

The solution is being piloted in 23 of Odisha’s 149 Urban Local Bodies, and early results are encouraging. It has eliminated the float and reduced payment delays by 57% to the beneficiaries—wage seekers and SHGs. The smart payments system can potentially save the Exchequer as much as USD 50 million for a state like Odisha.

The way ahead

The journey toward an effective and efficient government payments ecosystem in India has seen significant progress with the SNA-SPARSH model. While challenges persist, ongoing experiments and successful pilots demonstrate the potential for transformative changes in how government funds are released and payments are processed. The Department of Expenditure can plan one more reform on SNA-SPARSH to make payment processing based on rules triggered automatically through algorithms upon completion of work certified by the executing agency. It would make payment processing real-time. The vision of JIT payments may soon become a reality to pave the way for improved governance and better outcomes.
Thriving amid change: Agents in Indonesia’s evolving digital financial services landscape – Part 2

Our previous blog discussed agent networks’ remarkable growth in Indonesia. The agent network became more diverse between 2017 and 2023, which allowed multiple business models and provider practices to thrive. Despite its growth, longstanding challenges persisted, while new challenges emerged because of the networks’ increased scale. We discuss some such challenges below:

Lack of account opening services in agent outlets: Only 3% of bank agents offered bank account enrollment services—a decrease from the already low 28% in 2017. Inefficient e-KYC processes make the account opening or signing up process resource-intensive at the agent level. The process is manual, requires physical documents to be sent to bank branches, and takes one to two weeks to be completed.

Agents face liquidity management challenges: More than 60% of agents face barriers due to the unpredictable demand in DFS. The lack of working capital credit for agents exacerbates this problem. This is similar to the situation in 2017, when 63% of agents reported their struggle to manage liquidity.

Agents face increased incidents of fraud and robbery: Between 2017 and 2023, fraud against agents in Indonesia increased sevenfold in rural areas and tenfold in urban areas. 65% of agents are wary that their customers are most likely to commit fraud against them. This is a substantial cause of concern.

Provider compliance and risk mitigation measures remain inadequate: Provider compliance at agent outlets needs improvement. Only 14% of agents display tariffs, and only 42% display their agent IDs.

Providers struggle to train their agents adequately: Both banks and nonbanks struggle to provide refresher training. In 2023, only 19% of bank agents and 7% of nonbank agents received refresher training. Agents hesitate to sell new products without refresher training because they fear that they will make mistakes.

Providers have reduced support staff visits: 51% of agents reported that support staff visits have become less frequent as service providers rely on digital platforms for grievance resolution and communication. However, agents prefer in-person support staff visits to manage technical challenges.

Indonesia’s agent network has been instrumental in the extension of financial services to areas beyond Java Island and the urban regions. The amendments made by OJK and Bank Indonesia to Laku Pandai and e-money regulations in 2022 were forward-looking and aligned with global best practices. Regulators, service providers, and development partners must now collaborate to address challenges, foster innovation, and strengthen agent networks. Here are our recommendations to achieve this goal:

Recommendations for policymakers and regulators:

  1. Promote e-KYC infrastructure’s use to increase products and services available through the agent network

Indonesia has a substantial unbanked population. It also has recently improved its e-KYC infrastructure, which includes digital ID and face recognition services. Agents can bridge the gap in account access by facilitating account openings. Yet regulators and policymakers need to promote the application of agent-assisted e-KYC processes to accelerate account opening and mitigate additional costs to make this happen. These additional costs include expenses for biometric devices to prevent hindrances to adoption.

  1. Standardize training to improve agents’ capability with complex financial products

As agent networks expand, the provision of adequate training becomes challenging. This is especially important, given the introduction of complex financial products and rising digital fraud. Regulators should standardize training modules to maintain consistent service quality, particularly for full-service banking agents. They should also oversee these modules through regular audits to ensure compliance and effectiveness.

  1. Encourage transparency in the agent outlet to improve consumer trust

Regulators must prioritize customer protection and transparency, as most agents fail to display official tariff sheets or agent IDs. They must disclose transaction fees, product information, and grievance resolution mechanisms to ensure transparent services.

  1. Develop a supply-side database on DFS agents

The supply-side data on agents remains insufficient, especially on nonbank agents. Regulators must publish a regular and comprehensive database of agents. It will help assess the progress of financial inclusion and serve as a critical input for evidence-based policymaking. The database should include gender-disaggregated data for bank and nonbank agents beyond agent numbers and locations.

Recommendations for service providers:

  1. Use e-KYC services to expand product offerings to customers

Service providers should use advancements in the e-KYC infrastructure to deliver more comprehensive products and services through agents. This will enhance the agent network’s sustainability and extend financial services to marginalized communities, which will help integrate them into the formal financial system.

  1. Deploy third-party agent network managers to oversee agent operations

As the agent network expands in Indonesia, service providers face challenges when they seek to recruit, monitor, and train agents. They also struggle to provide support on liquidity management. Service providers should use recent regulatory changes to engage third-party agent network managers to provide comprehensive agent support services.

  1. Offer affordable and predictable lending products to help agents manage liquidity

Service providers can offer credit to DFS agents due to the digital nature of their business, which simplifies credit assessment as it provides clear digital trails. Per MSC’s research, lending to DFS agents in Indonesia is a USD 139–250 million opportunity, which is set to grow to USD 245–490 million by 2027. Service providers can innovate internally or collaborate with lending institutions to offer credit solutions that include working capital credit and loans for their CICO-adjacent businesses.

  1. Build internal systems and agents’ capability to detect fraud and build awareness to mitigate them

Wider adoption of DFS coincides with increased risk of fraud, both for agents and by agents. Service providers should help improve their agents’ ability to spot fraud. Service providers should also use digital media and refresher training to alert their agents about newer types of fraud and make them aware of such frauds to ensure safety.

Recommendations for development agencies:

  1. Work with service providers to catalyze and derisk innovations on new use cases for products or services available at the agent point

Despite the growth in transactions, most transactions at agent points are limited to cash-in, cash-out, top ups, and bill payments. Additionally, 80% of money transfer transactions occur over the counter. The full potential of agent networks will be realized when more individuals can conduct digital transactions independently and eventually access other financial products and services.

Development agencies can help advance new use cases that improve DFS use. This involves the promotion of research, development of proof of concepts, and initiation of pilots to test new products and services. Development agencies can also improve agent networks’ operational efficiency if they share the risks and costs associated with the development of these new products.

  1. Provide knowledge support to facilitate the transition from enhanced access to improved usage of financial services

Findings from the ANA 2023 research emphasize a need to shift policy focus from enhanced access to improved usage and quality of financial services. Development agencies can help improve agent networks’ regulatory and supervisory capability through research support, capacity-building support, and facilitation of exposure to international best practices. This knowledge support should extend to private sector stakeholders that intend to test innovative approaches to develop and manage their agent networks.

All stakeholders must work together to tackle the challenges and maximize the opportunities in Indonesia’s changing agent network. Meeting Indonesia’s financial inclusion targets demands efficient coordination among policymakers, service providers, and development agencies. This collective endeavor will empower agents, speed up financial access, and drive the sustainable expansion of Indonesia’s agent network.

For a complete overview of the recent findings, you can view the full Agent Network Accelerator (ANA) Research – 2023 report here.

From rural roots to digital stars: Women’s journey to building e-commerce confidence!

Meet Neha and Sarita, rural women based in Alwar, Rajasthan. Neha is a confident business correspondent (BC) agent who uses her smartphone effortlessly for many things, such as e-commerce. In contrast, her neighbor Sarita uses a shared household smartphone her husband owns, which she hesitates to use for e-commerce. Then, one day, Sarita’s fate changed when she tapped into her community and reached Neha, who inspired her to master e-commerce platforms.

This blog charts a journey from uncertainty to confidence through a community of practice (CoP) in the era of the digital divide.
(Learn more about MSC’s work on CoP). In this internet age, e-commerce enables entrepreneurs to access larger markets and diversify their income streams. It also helps users, especially women, reduce their dependency on traditional and often less accessible market channels. Thus, it increases their economic independence.

Community of practices: A step closer to bridge the gender divide

As per the Findex data 2021, about 80 million customers aged above 18 years made their first digital merchant payment during the COVID-19 pandemic. Almost 95% of all Indian districts have access to e-commerce platforms. Yet, disparities persist between the urban and rural areas. As per GSMA’s “The State of Mobile Internet Connectivity 2023” report, 10% of Indian smartphone users do not use the Internet, while 37% of the rural population is unaware of the Internet, and 15% do not know how to use it on a mobile phone.

Gender inequalities continue to plague the digital world. Women lack regular access to technology and digital products. As per GSMA’s “Mobile Gender Gap Report 2023,” women are 40% less likely to own a smartphone and use mobile Internet than men. Women’s usage of smartphones and the Internet in India for digital payments is 17% less than that of men, as per the Global Findex Database 2021. Their digital proficiency with smartphones and the Internet is limited to calling, short message service (SMS), and social media, such as WhatsApp and YouTube.

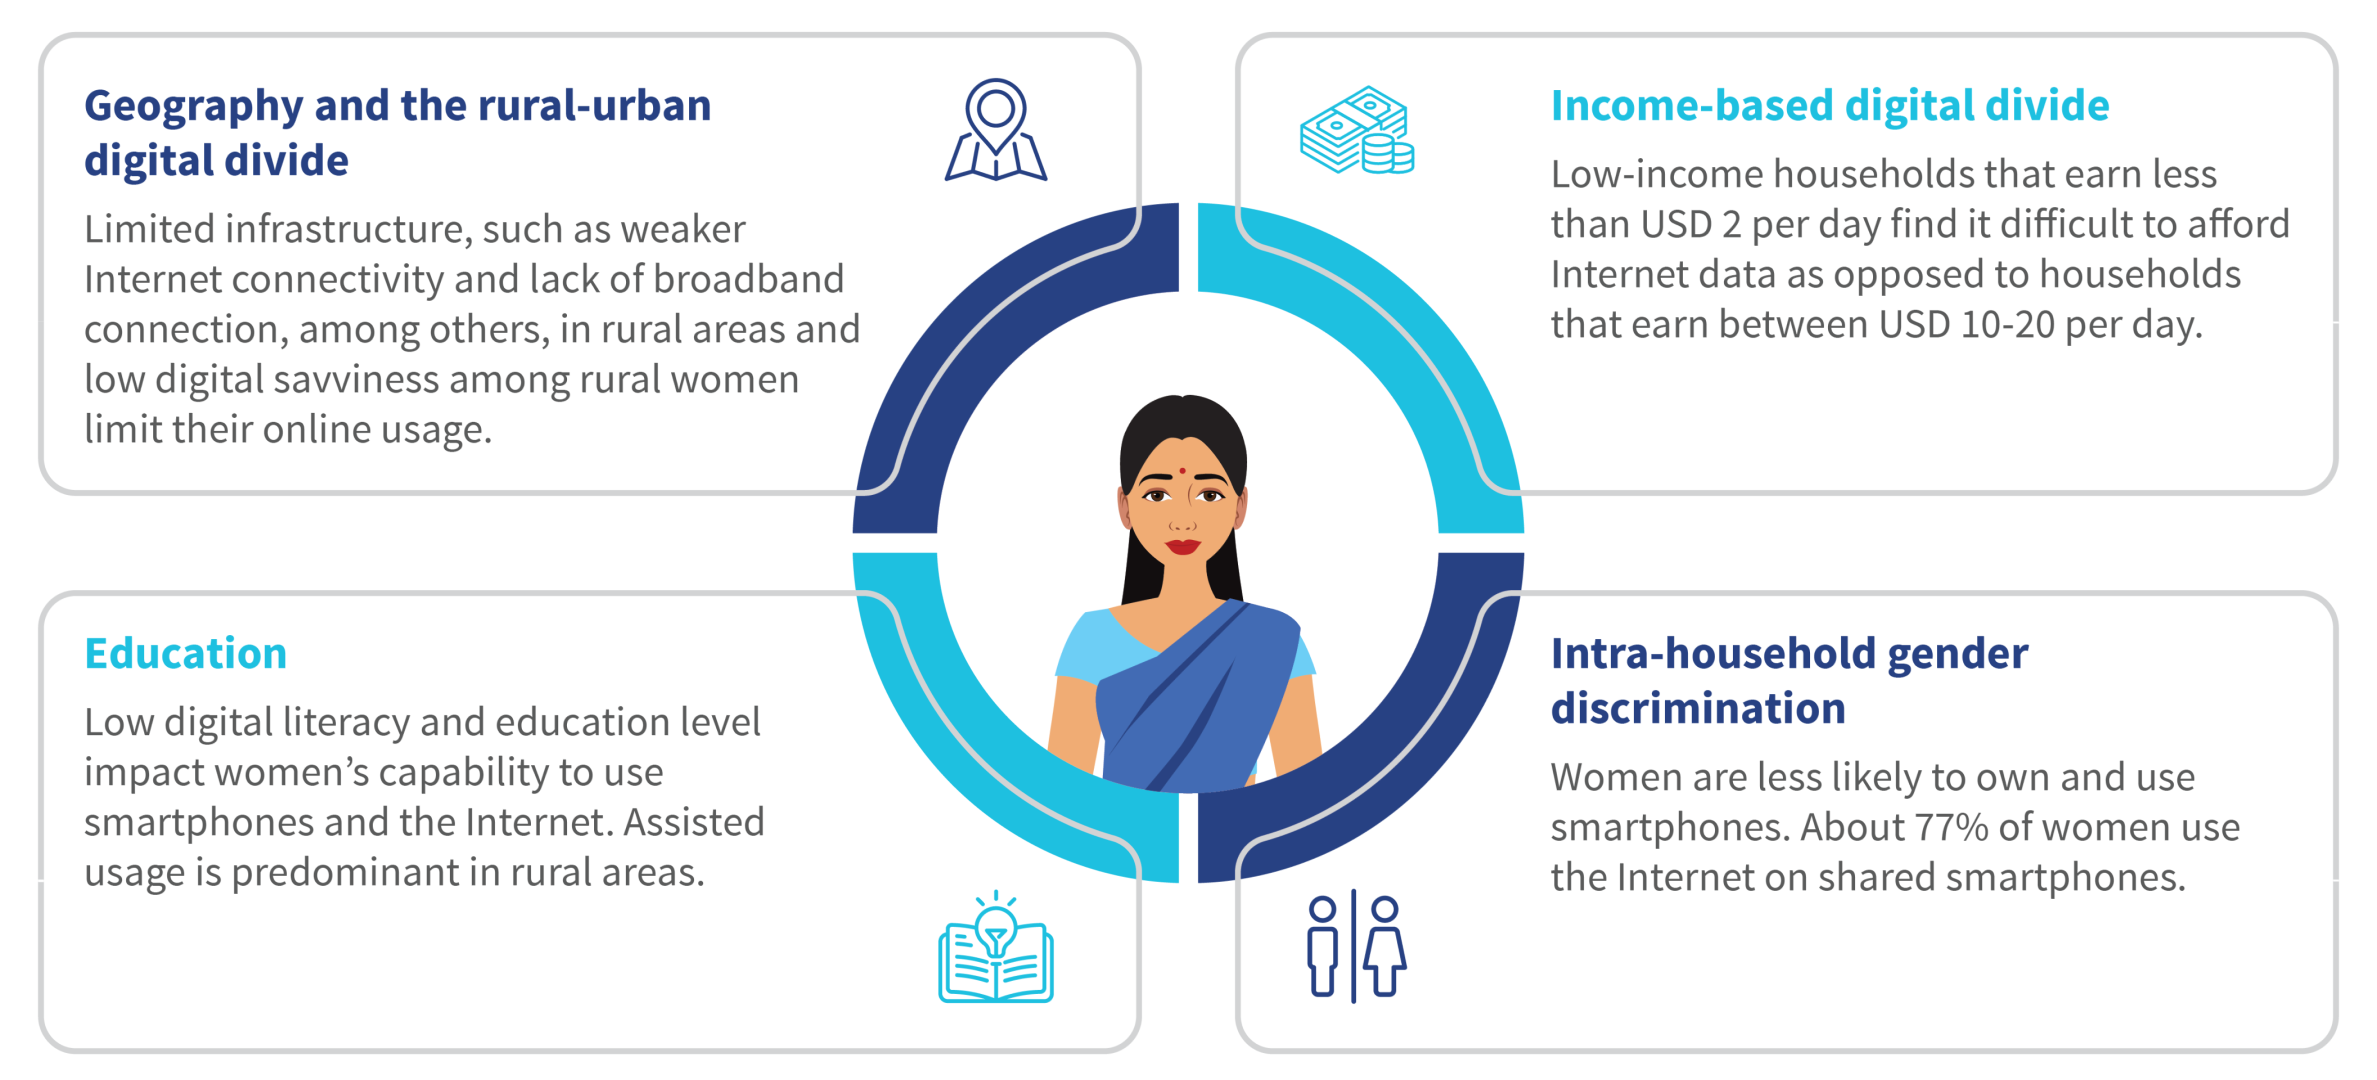
Primarily, four factors contribute to the digital gender divide:

Figure 1: Four key factors that contribute to the digital divide


We can significantly enhance women’s proficiency in e-commerce if we actively build their capacities. While this is easier said than done, MSC’s ground-level work with Frontier Markets provides a ray of hope as it builds and sustains a localized community of practice (CoP).

Driving women’s participation through CoP: Offline and online channels

A CoP is a “collaborative network where individuals bond over a shared interest or field and engage in collective learning and expertise development.” A CoP can play a key role to drive initiatives on the ground through peer-to-peer (P2P) learning and encourage more women to use e-commerce on the demand side as customers and the supply side as entrepreneurs. For instance, a field visit with Frontier Markets in Rajasthan revealed that women were eager to develop their capacities, diversify their income, and strengthen their financial resilience through e-commerce.

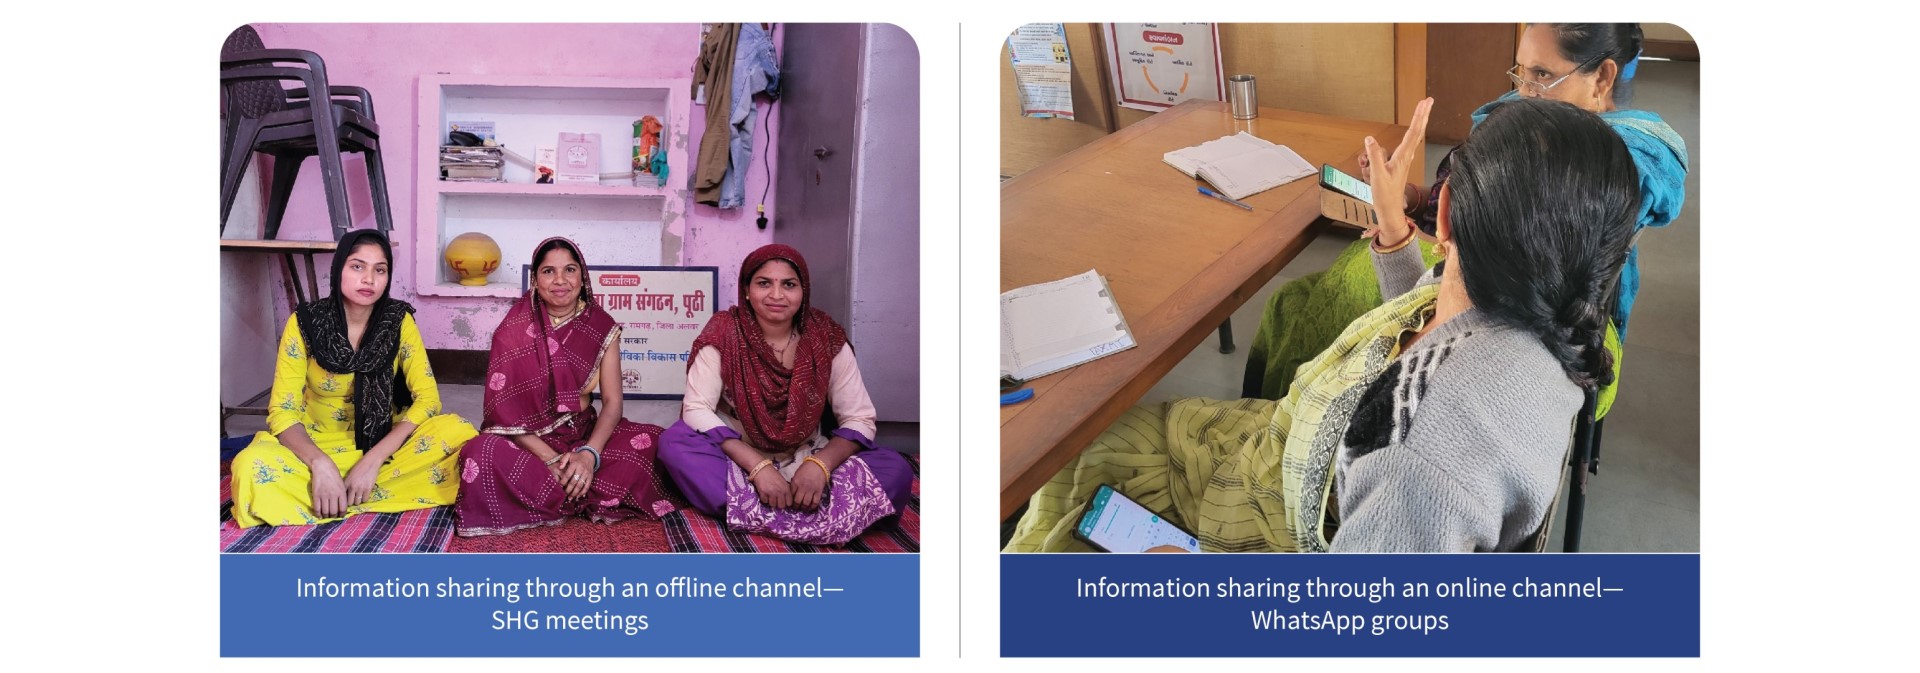
Stakeholders can build CoP initiatives through both offline and online channels. Offline channels include SHGs, while online channels include platforms, such as WhatsApp, Facebook (Meta), YouTube, Meesho, and Frontier Markets’ Meri Saheli” application. CoPs can empower rural women to use the Internet and smartphones for e-commerce.

Figure 2: Rural customers as they share information through offline and online channels

Offline channel: SHGs (self-help groups)

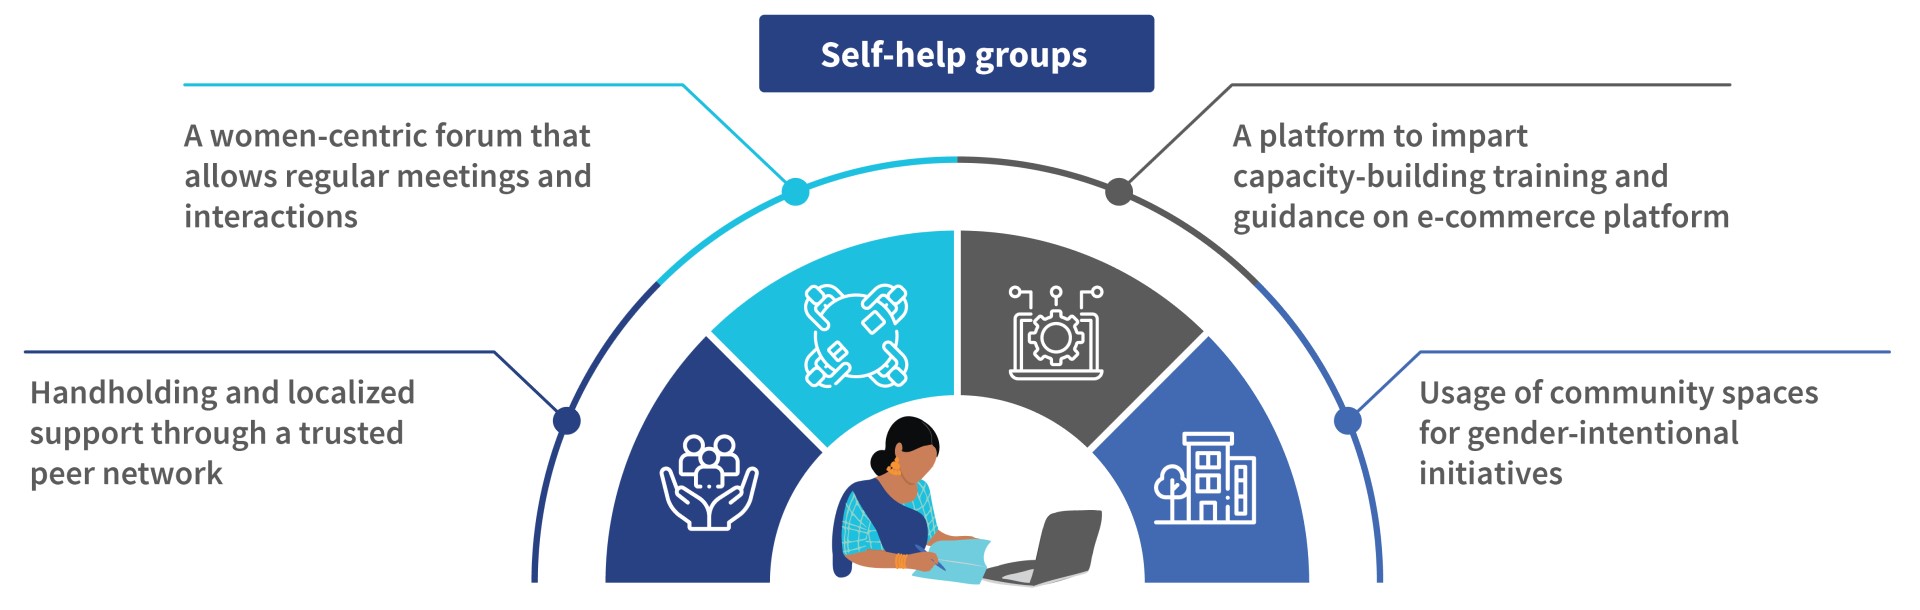
Several women entrepreneurs are part of SHGs. They come together and discuss group members’ financial needs, aspirations, and challenges, share expertise around their primary occupations, and organize skill-building activities to support each other. This creates a collaborative environment where women learn and grow. These existing institutions, therefore, serve as launch pads for the women entrepreneurs to build localized CoPs, upskill, and scale their businesses. These women also share their success stories and help other women in their community use technology to benefit their businesses.

For instance, during MSC’s fieldwork with Frontier Markets in Rajasthan, we observed that female BC agents actively promote digital transactions on e-commerce platforms and at BC agent points.

Figure 3: Key highlights of the SHG offline channel


Additionally, SHGs provide a platform for financially and digitally proficient women to build their peers’ capacities and offer guidance. For example, Frontier Markets has a strong network of Sahelis in rural Uttar Pradesh and Rajasthan, which builds rural women’s capacities to place orders on e-commerce platforms and conduct person-to-person (P2P) and person-to-merchant (P2M) digital payments. These women entrepreneurs’ efforts catalyze the businesses of other women entrepreneurs through technology-driven tools and platforms.

The use of community spaces for offline channels

Although CoPs are a stepping stone where women entrepreneurs share lessons with each other, social constraints deter women from gathering in common places. However, women can overcome social constraints and engage in SHG activities when they generate income for the household, provide access to financial services in the community closer to home, and build their identity. Community gatherings in the panchayat office, the primary health center, and schools, among others, can emerge as a channel through which women teach each other how to use e-commerce platforms and conduct digital payments.

Online channels: A potent option to drive CoP

CoP thrives on knowledge sharing and peer learning. Besides SHGs, where women share information in person, digital platforms also provide women with a channel to share information and learn from each other.

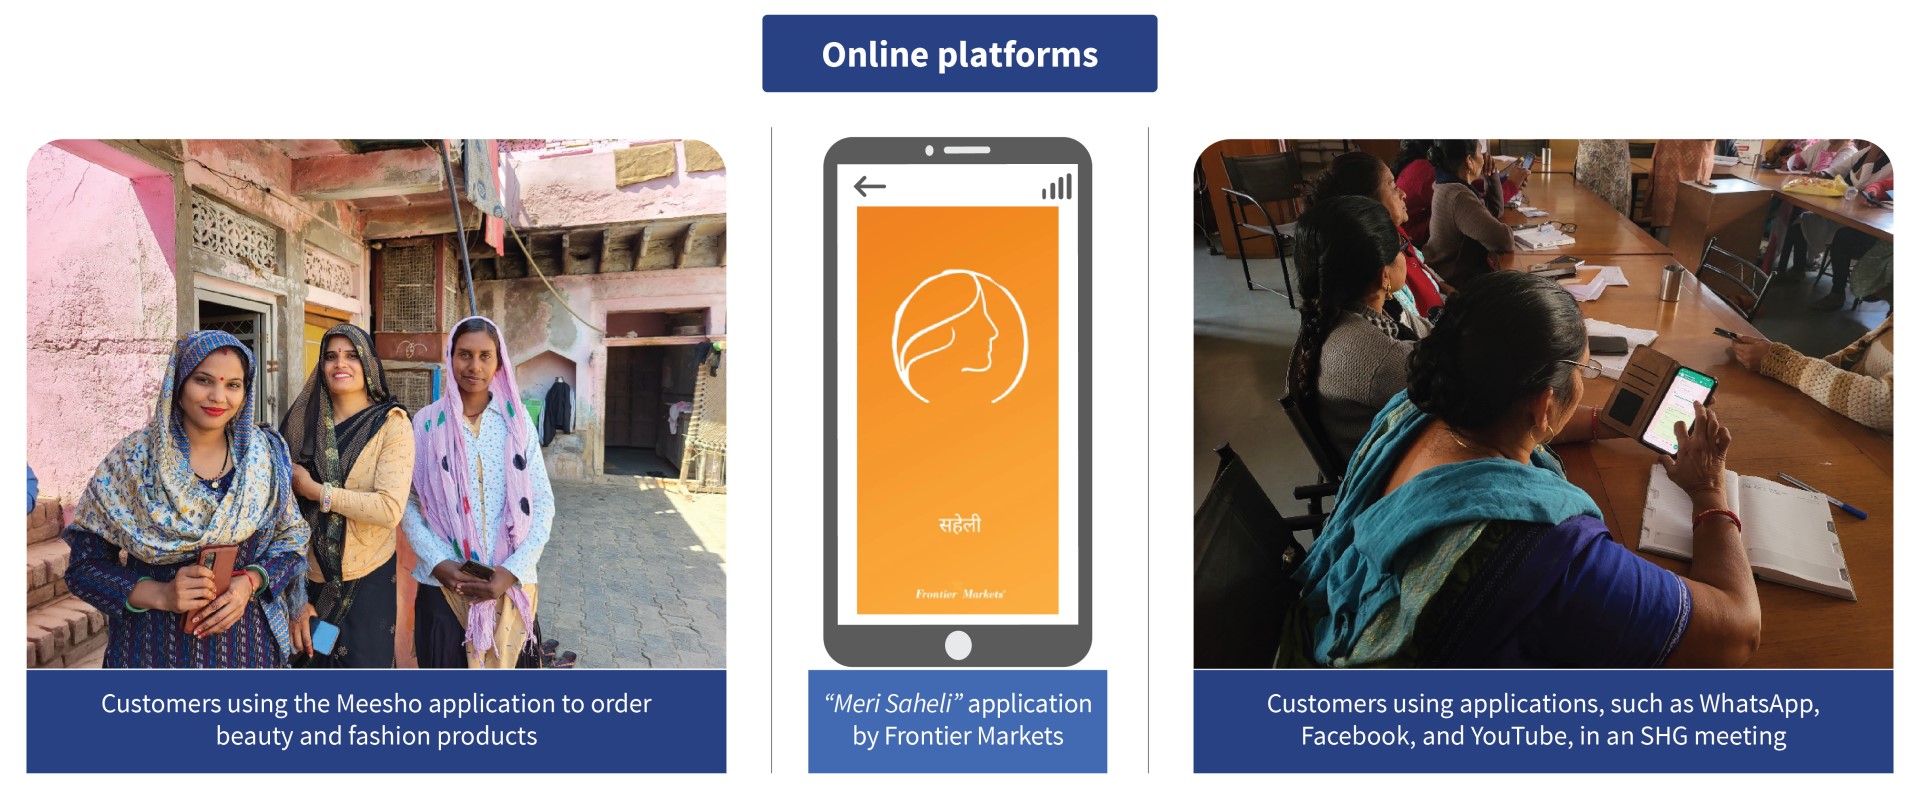
Many rural women often use digital applications, such as WhatsApp, YouTube, SMS, and phone calls. A few also use e-commerce or social commerce platforms, such as Amazon, Flipkart, Meesho, and the “Meri Saheli” platform, to buy products independently or with Saheli’s assistance. These self-initiated and assisted transactions clearly demonstrate the use of technology and the key role technology plays to grow their business and build awareness in their community. The following section outlines some platforms we see in action on the ground.

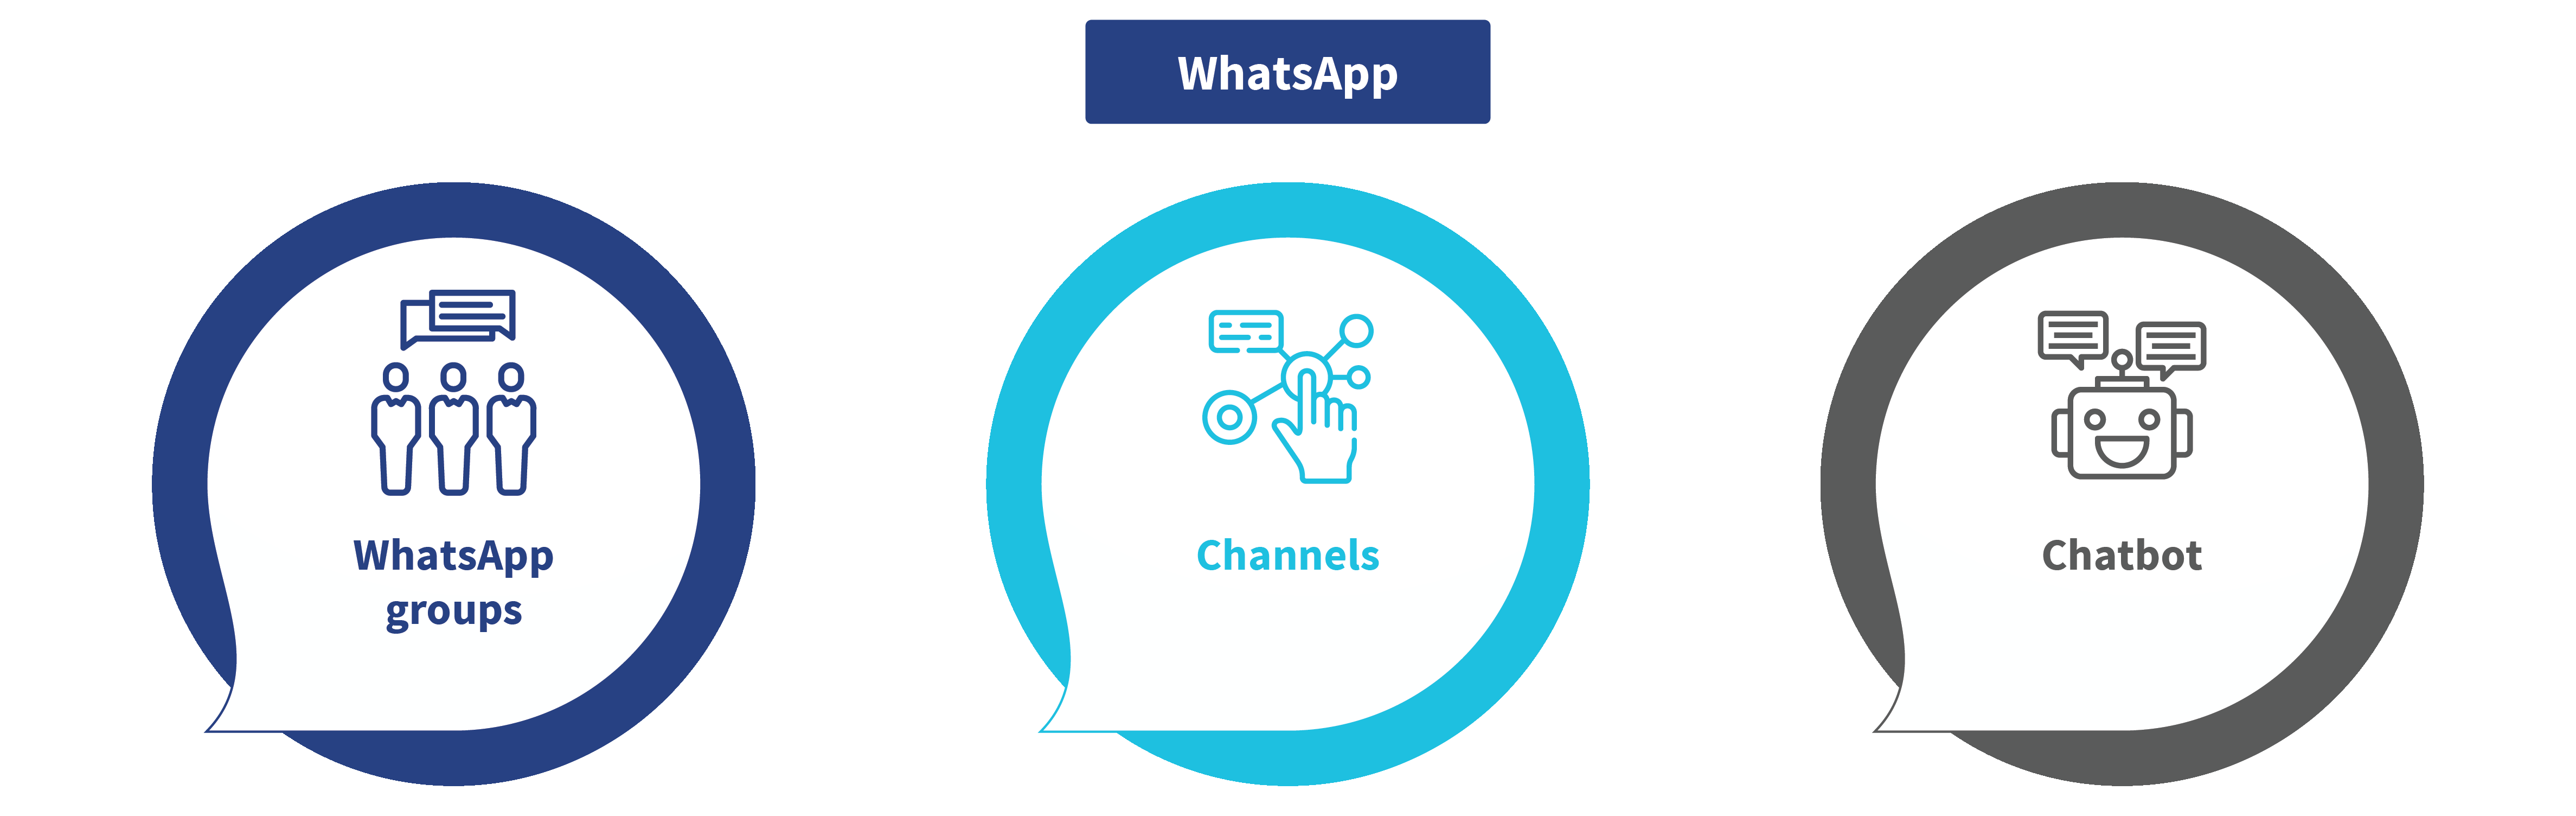
Virtual groups, channels, and chatbots on WhatsApp encourage knowledge sharing and absorption. Geography-specific WhatsApp groups and channels at the SHG or CLF (cluster level federation) level create a platform for women who want to learn how to conduct digital payments and buy and sell products on e-commerce to exchange information regularly. For instance, Frontier Markets encourages engagement among Sahelis and rural women through WhatsApp groups, where they learn about digital payments and advanced agricultural inputs, such as climate-resilient seeds, liquid fertilizers, and animal nutrition.

Figure 4: Frontier Markets used these three features of WhatsApp to share information with women


Platforms, such as Facebook, Meta, and YouTube, equip rural women with diverse skills, such as digital payments, vocational education, and farming. This strengthens their employability and income-generating potential. Moreover, platforms, such as Meesho and the “Meri Saheli” application, enable rural women to access essential household products conveniently. Through these platforms, rural women gain familiarity with digital payment modes, such as UPI (Unified Payments Interface) and QR (quick response) code-based systems (PhonePe, Paytm, and Google Pay). This streamlines their experience to conduct digital financial transactions and build their digital footprints.

Figure 5: Rural customers using online platforms

The way ahead

CoP initiatives through offline and online channels can help rural women like Sarita develop their financial and digital proficiency and bridge the digital divide. Tapping into the local leadership’s potential and skill sets of financially and digitally proficient women can develop rural women’s capacity to use e-commerce. With an active CoP and willing service provider, many women like Sarita can access larger markets, diversify their income streams, become economically empowered, and enhance their financial and digital literacy.

State of the agent network in Indonesia: Agent Network Accelerator (ANA) Research – 2023


Indonesia’s agent network landscape is dynamic. It witnessed significant changes in recent years, which include a proliferation of service providers and the emergence of various business models. Moreover, external factors, such as COVID-19 and regulatory and policy changes, have shaped the network’s growth. The Agent Network Accelerator (ANA) 2023 research is the biggest-of-its-kind survey of DFS agents in Indonesia that delves into some of these changes. This crucial benchmark compares the agent network’s growth in 2023 with the ANA research in 2017 and features participation from 2,644 agents countrywide. Read on as we track these changes and examine their implications for agent sustainability in the “State of the agent network, Indonesia 2023” report.

Smart payments playbook: A guidebook to implement smart payments in the government payments ecosystem

The government still struggles with loopholes in payment delivery to states and agencies that work at the last mile. The smart payments solution can enable frictionless expenditure, decrease administrative burden, and increase accountability in their payment processes.

This playbook seeks to facilitate the smart payments framework’s practical applicability for various government payments, whether it is government-to-government (G2G) payments, government-to-businesses or contractors (G2B), or government-to-persons (G2P). It will allow them to identify gaps in their current processes and implement smart payments as an effective solution.

It can also be a reference for any government department that wants to automate its payment processes. Access the playbook here.

Thriving amid changes: Agents in Indonesia’s evolving digital financial services landscape

Rizal is a 35-year-old DFS agent in a peri-urban area of Padang city in West Sumatra. He offers services from multiple providers and switches seamlessly between different apps on his smartphone to handle various customer requests. He rebalances his account through a third-party provider that delivers cash or float at his outlet.

Rizal has been an agent for more than five years and manages around 30 daily transactions across one bank and four nonbank providers. This enables him to offer more competitive pricing as he can curate services across providers to match customers’ needs. This attracts a diverse customer base and leads to higher transaction rates.

In contrast, Amir is a dedicated agent who offers his customers a single bank’s services. His kiosk is located in a rural village not far from where Rizal operates. It features the bank’s marketing collateral and mimics the look and feel of a bank branch. Amir took advantage of the high demand for financial services and low agent concentration in the area to expand his business and added three additional outlets in the vicinity. Amir travels to the nearest ATM or bank branch to rebalance his accounts.

Rizal’s non-exclusive provider approach contrasts with Amir’s dedicated and exclusive focus on one provider. However, both arrangements earn profits. Indonesia’s agent network has evolved to enable multiple business models and diverse practices to offer financial services to the last mile. This diversity enriches the market, offers consumers different options, and fosters innovation and accessibility to DFS.

Rizal and Amir are among thousands of agents in Indonesia who provide financial services to the last mile and play a crucial role in Indonesia’s financial system.

Over the years, Indonesia’s agent network landscape has undergone significant changes. Service providers have proliferated while different business models have emerged. Moreover, events, such as COVID-19, alongside regulatory and policy changes, have shaped the network’s growth. Indonesia’s agent network landscape needed further investigation into the changes underway and their impact on agent sustainability.

This need spurred MSC to undertake the third phase of the Agent Network Accelerator (ANA) research in 2023 with funding from the Bill & Melinda Gates Foundation. It serves as a crucial benchmark that compares the agent network’s growth in 2023 with the last ANA research in 2017. The ANA 2023 research also included the biggest-of-its-kind survey of agents in Indonesia, with participation from 2,644 agents countrywide.

The following section highlights key trends in Indonesia’s agent networks in 2023.

The agent network in 2023 was more diverse, although still dominated by banks

Indonesia’s agent network has doubled since 2017, with more than 1.5 million bank agents in 2023. Public sector banks, such as BRI, BNI, and Mandiri, dominated the agent network, while FinTech companies and e-commerce players also established their agent networks.

Women continued to constitute the majority of agents in 2023, which mirrored the trend observed in 2017

Indonesia’s agent network continued to be gender-balanced. 55% of DFS agents in 2023 were women, compared to 59% in 2017. Per ANA 2023 findings, male and female agents did not have performance or income disparities. The operating hours of the agent outlet also had no gender disparity.

Agent retention rose in 2023, which implies reduced turnover

In 2023, 30% of agents were working as an agent for more than five years, while 51% worked in the agency business for more than three years. This marks a shift from 2017 when 75% of agents had less than two years of experience. This indicates reduced agent churn in the agent network.

Agents were more profitable, which enhanced the agent network’s sustainability

The median daily transactions for agents increased fivefold between 2017 and 2023. Services, such as top ups, bill payments, money transfers, and cash-outs, drove this growth. Improved stability in the agent network after the pandemic and the slow growth of new bank branches and product use cases contributed to this growth.

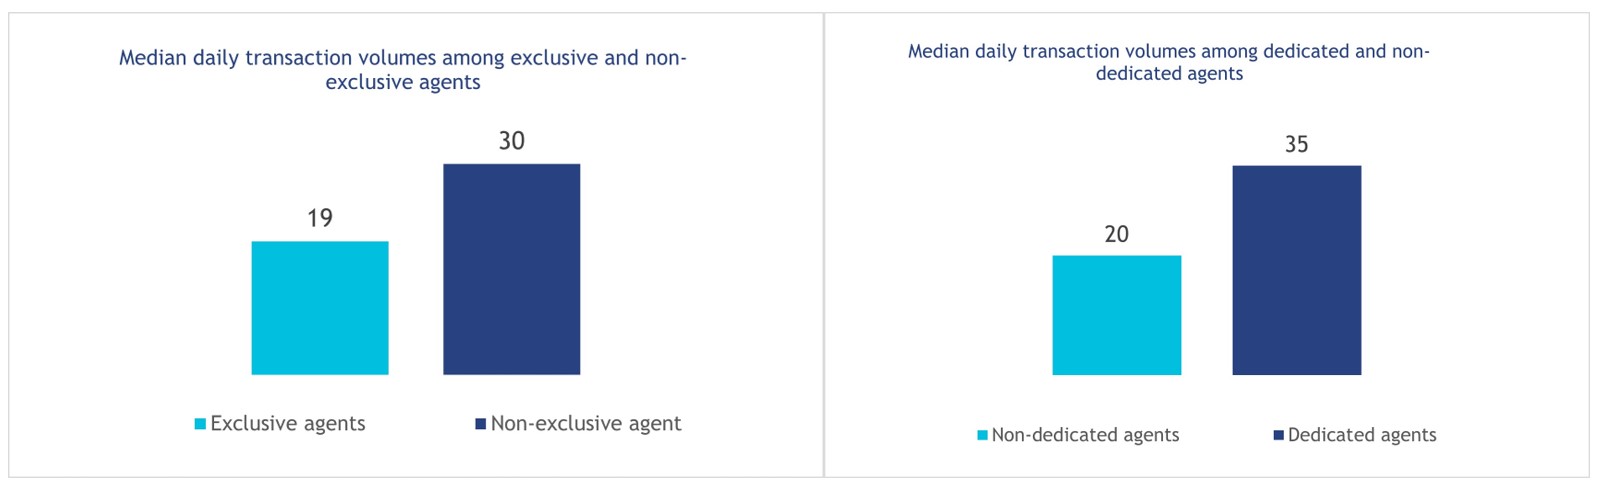
ANA 2023 revealed that agents outside Java experienced more daily transactions than agents in Java due to a sparser agent network and high demand in non-Java areas. Additionally, non-exclusive and dedicated agents achieved higher median transaction volumes, as depicted in the graphs below.

The study shows that increased transactions have made 95% of active agents profitable. The median monthly profitability had grown from USD 6 in 2017 to USD 134 in 2023, which represented a CAGR of 68%. Bank agents were three times more profitable than nonbank agents because they handled more high-value transactions, such as money transfers and cash withdrawals.

Non-exclusivity among agents grew while the proportion of non-dedicated agents declined marginally

Exclusivity, as calculated by the number of agents who offer the services of more than one service provider, decreased significantly from 97% in 2017 to 75% in 2023. However, the Laku Pandai regulations on exclusivity, which prohibit agents from offering services from two different banks, reduced exclusivity among bank agents by only 5%.

Most agents in Indonesia are non-dedicated. However, the proportion of dedicated agents has increased significantly, especially outside Java, which has risen 8% since 2017. A high demand for financial services and low agent concentration in islands outside Java make it profitable for agents to remain dedicated.

Agents, especially bank agents, offer more products and services through their outlets

More bank agents have expanded their services to offer insurance and online virtual (VA) payments. Increased access to public insurance (BPJS) and the growing use of online platforms in rural and urban areas drove this shift. However, nonbank agents continue to rely on top ups and bill payments for their transactions.

ANA 2023 also found that about 20% of all agents adopted QRIS payments. Although DFS agents are the ideal target segment for QRIS adoption, the adoption rate is low due to the long settlement times for QRIS transactions.

Meanwhile, the adoption of e-commerce among agents remained limited to personal consumption and did not expand business revenues.

During the 2017 ANA survey, agents expressed strong optimism about their agency business’s potential. This optimism translated into remarkable success in 2023 as agents became more profitable and sustainable.

In our next blog, we will discuss the challenges in the agent network and propose recommendations for different stakeholders to strengthen Indonesia’s agent network.

For a complete overview of the recent findings, you can view the full Agent Network Accelerator (ANA) Research – 2023 report here.