The need for a branch infrastructure and managing high volumes of low value transactions are the barriers related to serving the low-income market. While outlining the features of mobile banking, the note warns that the failure of such initiatives is often due to its inappropriateness to address the customers’ needs rather than because of technological problems. The note also highlights the reasons as to why should low income segment prefer technology—if it is secure, convenient, low cost, accessible/liquid and easy to transfer. It also compiles the barriers and challenges in using technology like availability of machine, lack of training, lack of sufficient funds with agents, illiteracy among clients, lack of willingness from suppliers and other resource constraints. It also highlights the significant role played by cash and its functionality.
Blog
Feedback loop analysis: Key lessons in the financial service delivery
This paper shares key issues on feedback loop analysis drawn from MicroSave’s experience under its Action Research Programme (ARP). Detailed analysis of feedback loops has been performed at Tanzania Postal Bank (TPB), Equity Bank and Kenya Post Office Savings Bank. The paper defines the feedback loop, details the process of analysing the loop, discusses different feedback mechanisms and then develops key lessons for the industry.
Catalysing Capacity Development: Assessing the Need for Training
This note summarises the key findings and recommendations of a study conducted by MicroSave to understand and analyse the need for training/capacity development, optimal contents and structure of training courses as well as the organisations/institutes best placed to deliver training in the different regions of the country. The key findings and recommendations revolves around—identifying suitable trainings, following adult learning best practices, use classroom plus on-site follow-up technical assistance, developing an integrated microfinance curriculum, comprehensive training packages in India, and targeting of inputs in a clear and legible ways.
Microfinance Institutions and Salary Based Consumer Lending
This note draws on the experience of MicroSave’s Action Research Partners (ARPs), involved in providing consumer loans to low income salaried workers. Under these loans monthly deductions are made from salary accounts maintained with the financial institution or payments are made through direct payroll deductions and remittance in the lender’s accounts. It cautions the MFIs which intend to provide such loans that these loans can outstrip funds very quickly. It also suggests managing risks and explains the strategies such as using pilot tests to identify operational constraints, managing employer-employee relationships, controlling repayments, ensuring affordable loans to customers, strengthening credit control and administration, and using technology for further reducing the risks.
Grameen II – The first five years 2001-2005
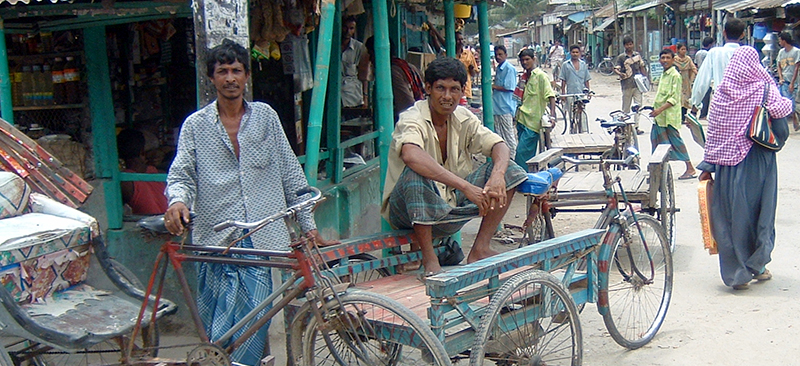
MicroSave conducted a study in 2006 to understand the transition of Grameen Bank in Bangladesh to Grameen II. The study was carried out by Stuart Rutherford in association with MicroSave. Grameen II is only a partial redesign of the classic Grameen model, focused mostly on changes in the range of products offered and their terms and conditions.
Grameen II offers more need-based services to the clients and also makes access to these services significantly easier. Processes have been simplified and streamlined. The staff have been trained in better process management to handle the volume of transactions involved to deliver efficient functioning. The other dimension considered was portfolio diversification through renewed emphasis on public deposits. Besides, new and attractive services such as the special savings account, special purpose loans, etc. based on client demand were introduced.
The study also highlights the areas for improvement for a possible Grameen III to emerge, such as better use of information technology, better marketing of products and services offered and desirable regulatory environment for emerging players in the microfinance sector in Bangladesh.
Costs and benefits of market research and pilot testing for new product development in microfinance
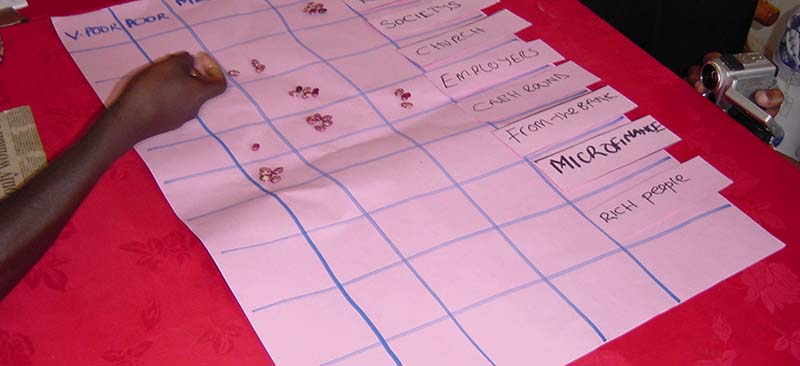
To attract and keep clients, Microfinance Institutions (MFIs) want to introduce new products that meet these demands. One of the most pertinent questions facing many MFIs today is “how?” Significant resources have been invested in the research and documentation of a market-led approach to product development, which is now widely accepted by the microfinance industry’s technical service providers.
The approach includes five steps, two of which—market research and pilot testing—have rarely been adopted by MFIs, despite the fact that they are the core of the client driven approach. Why is it so, is a matter open for discussion.
Drawing from existing literature and the experiences of ten case study MFIs in seven countries, this document explores that hypothesis and summarises the costs and benefits recorded by institutions that have chosen to incorporate market research and pilot testing into their new product development processes.
