Blog

Teaching Elephants To Tango: Working with Post Banks To Realise Their Full Potential

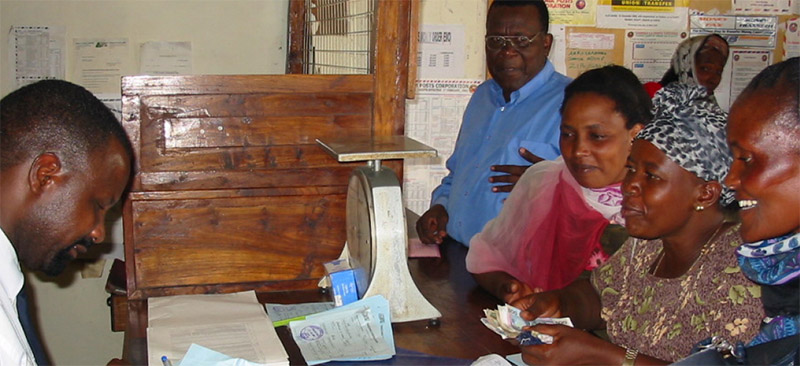
MicroSave carried out a SWOT/ PEST Analysis on the Tanzania Postal Bank (TPB) and the Kenya Post Office Savings Bank (KPOSB) to explore the possibility of Post Offices offering microfinance services as a value added services to their poor clients. The Post banks’ existing large network of branches gives them indisputable comparative advantage and the potential for linking these to e-banking solutions offers a real possibility of bringing the financial services to the unbanked in poor countries. The publications explores ways by which post banks’ network can support the government and other institutions in making salary and pension payments to people living in remote areas who are otherwise un-served by commercial banks.

The document highlights the comparative advantage of post banks’ networks over shops, garages and bars which are used as E/M-Banking agents. For instance, in some countries, the central bank authorities do not permit such outlets to offer even basic withdrawal service. However, the post banks typically remain subject to restrictive policy environment such as labour laws that limit their ability to follow efficient human resource management and product development practices.

The paper goes ahead in making recommendation that in the future even commercial banks can foray into microfinance and even remittance services. A level playing field between the public and the private sector is called for to offer public choice to the consumers in financial services’ delivery.

Point-wise SWOT/PEST analysis conclusions can be read in this article.
Do Microfinance Institutions Really Need to Worry About Their Brand?

This paper documents experiences of MicroSave’s Action Research Partners (ARPs) in strategically building a corporate brand to reach more clients, increase profitability and become more market-led. The principles outlined are drawn from MicroSave and Women’s World Banking (WWB)’s Corporate Brand and Identity Toolkit.

With increasing competition in the microfinance sector, it would be unrealistic for MFIs to assume that customers would not switch to other providers. Consequently, the industry is moving towards a more market-led approach in which financial service providers are re-oriented towards researching and responding to customer needs. Given these conditions a strong, well-defined corporate brand becomes the key to reaching and retaining more target clients.

This paper highlights the need for MFIs to realise the power of corporate brand and provides insights into the process of brand building that can assist financial service providers in designing their strategy for brand development, implementation and monitoring.

Developing Cash Flow Based Micro and Small Enterprises Business Loans- The Experience of Equity Bank with Biashara Imara

This note highlights key lessons from the experience of MicroSave’s partner Equity Bank, in designing, testing and rolling out a cash flow based individual business loan product. It finds out the reason of Equity to venture into cash flow based micro credit was driven by a realisation that there was a substantial, and largely unmet, demand for this type of product. The note describes about the processes undertaken in the pilot tests of the product and the positive consequences on policies, procedures, pricing decisions, staff training requirements and remunerations. The note further highlights the key lessons learned in pilot testing—following a well structured process, conducting designing research, ensuring capacity and support, building MIS, procedures, and establishing monitoring systems.

The Art and Science of Pricing Financial Services

This paper briefly examines pricing as a determinant of customer’s choices. It tries to assess why pricing financial services are so difficult for users to understand. It also considers the pricing implications in evolution of “market-led” approach from “traditional” microfinance approach.

The paper also lays emphasis on the significance of transparency and mechanisms and policies to improve pricing transparency. It concludes with suggestions on how to price products and factors relevant for pricing different types of financial services, including savings, loans and e-banking products.

Games Loan Clients Play

Generally the clients of financial service providers either test controls, exploit weaknesses in their system or test the institution’s capacity to live up to its promises. This note discusses some of these tactics used by the clients individually or in a group to avoid payments and possible solutions to the financial service providers. Some of the games played by the clients are mobilising ghost clients, involving family members, servicing loans of a drop out to get higher loan amounts of next cycle, prepayments, loans from other MFIs on the same business in the names of their friends or relatives, false guarantors amongst many others discussed in this note. The possible solutions, as the note suggests, range from immediate follow up to setting up internal audit team and loan portfolio audit.

A Critique of GB II’s Means Test for Membership 

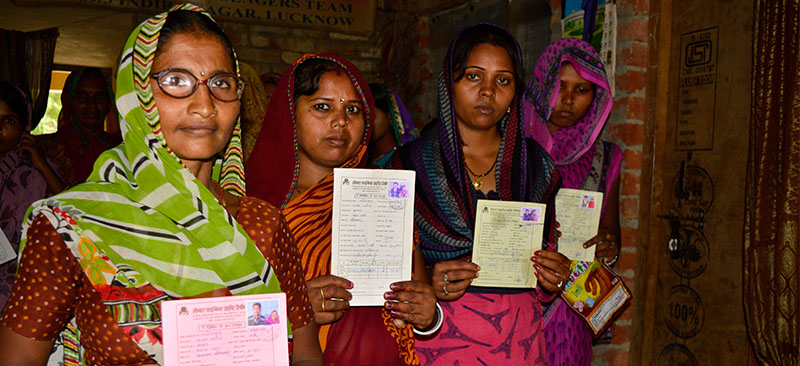
In early 2004, Grameen field staff began using revised guidelines to determine whether applicant households qualified as poor enough to become members (that is, eligible to borrow from the bank). The new guidelines maintain the focus on land and asset ownership that has always characterised Grameen’s means test (and been copied by most MFIs in Bangladesh). However, the new wording strengthens these rules by clarifying some ambiguities in their interpretation, and amplifies them by adding a note on the kinds of people who should be prioritised in the search for new members and who should not be considered for membership. This note explains the intricacies of these new guidelines and offers three criticisms of the new methodology: 1) the specified levels are set too low, resulting in too restricted a pool of eligible applicants; 2) they are in practice unworkable, leading field workers to find ways around them; and 3) they represent a missed opportunity to construct a useful database on membership.